07 May 2007

Prada at Kmart: luxury brands and status abandonment.


It's only a small thing. But as we all know small things can lead to big things.

But the release of a new Prada fragrance, Tendre (selling for $79.00) in the Sydney Mother's Day catalogue for Kmart Australia, certainly signals to DIFFUSION that Prada seems to be heading down the same road of luxury brand dilution that destroyed the once great Pierre Cardin, nearly brought down the house of Calvin Klein and which threatens so many brands in this market.

Sure you might argue that it's only perfume and for this brand a cheaply priced one at that, but the democratization of luxury brands seems to be destroying those aspects of a luxury brand (exclusivity, price, access, aeesthetic) that denote these brands.

It's fact we noted in our blog The Defining Essence 20 October 2005 and one that seems to have escaped Prada's owners as they take the brand into the mass luxury market.

Perhaps the Prada licensees haven't read the definition of luxury that in 2000 the European Commission used to review Prada's role in the market as part of a ruling on it and LVMH's acquisition of Fendi. What's important about this ruling is that it is one of the few non-academic reviews of the operation of luxury goods.

The Commission described "luxury products" as "high quality articles with a relatively high price, marketed under a prestige trademark". As such luxury goods were considered to operate in a single product market because of two factors "substitutability from the demand side: the idea of acquiring a luxury good is linked to prestige rather than consumption of a precise item" and "substitutability from the supply side" or where most of the producers of luxury goods manufacture a broad range of products such as ready to wear, leather goods, fashion or, in this case, perfume.

This definition fits in comfortably with our understanding of both the pricing and accessibility attributes of luxury brands. More importantly, the definition attaches the generally accepted idea that prestige is also linked to acquisition and not the actual consumption of the item. Which is probably to say that a lot of women will see the Kmart catalogue and think "I have to have this Prada perfume because it is a such a luxe brand".

What's also interesting from this ruling is the Commission also connects both the transactive distance of luxury brands and the aesthetic of their environmental setting to their definition, noting that Prada itself indicated that "the common denominator is the importance of qualitative requirements designed to maintain the image of prestige, exclusivity and the high quality of the brand (e.g. location, the nature of the external appearance of neighbouring shops, decoration and fittings of the outlet which should reflect the prestige of the brand)."

This hardly sits well with my knowledge of my local Kmart located in a suburban shopping mall which hosts a Baker's' Delight, Go-lo and a Wendys and where Prada perfume is likely to sit alongside the latest offering from Paris Hilton in aisle six.

So, by their own definition Prada not only seem to be falling out of the luxury goods market in their attempts to market mass luxury but also are defying some of the basic principles of luxury brand management. These are:

1. creating distance, a no-mix area or barriers to entry for those who are not invited and by necessity of protecting clients from non-clients;

2. selective pricing and and exclusive distribution as well as the aesthetic dimension of the products; and,

3. the recognition and acknowledgement of its luxury status by all.

By all three counts Prada is failing. First, by not maintaining and enforcing these barriers to entry and allowing their licensee to flout it. Second, by using a selective pricing model more recognisable as that of a democratic, basic brand model (other brands of perfume can sell at Kmart at similar prices) and finally, there appears to be both an acknowledgement of its luxury status by very inclusion on the front page of the catalogue, and also an argument for a case of status abandonment by Prada's Australian licensee and, I suspect, its international license holders, for this latest distribution deal. I'm sure it won't be first such breach.

03 May 2007

Ford and Rip Curl go beyond the wave.


Is Ford’s Ripcurl XR8 Ute Australia’s first co-branded car? It could be. Already a co-sponsor of a major Australian surfing title, the US manufacturer is doing some serious stretching in Australia alongside surfboard and clothing company Rip Curl.

While car manufacturers can piggyback on a large, loyal and extremely well profiled audience (think Ford vs General Motors Holden), it might also work if only to a niche market.

Hitching up with an existing youth brand seems like a good idea, especially if it’s an iconic Australian surf sport brand, like Rip Curl. And co-branding is useful as it helps reinforce the lifestyle image of the cars (how Australian is a ute after all, unless it's a panel van?) by linking in to an existing group of customers with similar tastes, lifestyle, or age. So it must be something that Ford has been missing out on as it seeks to bolster sales in a flagging demographic with the tie-in.

But it’s not Ford’s first foray into co-branding arrangements with clothing companies. Ford USA already produces SUV’s with lifestyle and clothing retailer Eddie Bauer (there’s a range of two and 4WDs in the 2007 series) and Subaru has teamed up with US outdoor clothing catalogue company L.L. Bean to produce the Subaru Gear range of outdoor apparel.

And there’s similar examples of between sports shoe and sports vehicle think Porsche and Puma, Adidas and Porsche, Ducati and Adidas, but mostly it’s been one way co-branding.

The most important thing for Ford is to make sure that the brand association works both ways, so that the target market segments don’t start to see it a just another multinational muscling in on a cool brand. Beyond the Rip Curl extras, what really makes this is a true Ford brand experience? What preserves brand attributes?

Importantly for Rip Curl, they should be wary that there is no diminution of their own brand by the target segment (as seen in the current Australian television advertising) but also by future target segments and this will require some strong brand management.

Australian wine is a glass half full.


Australia’s wine industry recognises it's glass is half full and now wants to reposition Australian wine at the premium end of the market.

This week the Australian Wine and Brandy Corporation and the Winemakers Federation of Australia unveiled their Wine Australia: Directions to 2025. The Directions paper, which in a rare case of both industry cooperation and speed of report writing, was commissioned in 2006 and recommends 46 directions to be adopted by winemakers and marketers in coming months.

According to the report, Australia’s wine industry must” focus on strengthening sector structures, directly influencing domestic and export markets and gearing up for sustainable success.”

“The Australian wine sector needs to re-evaluate its current approach towards export markets. It needs to identify new and sustainable market opportunities through detailed market intelligence, and turn consumer interest into aspiration through segmented marketing strategies. In particular, this only can be achieved by raising awareness and expectation of an Australian wine story founded on an international reputation for regionally distinct and fine wine production. Further, it also needs to refocus its expectations in the domestic Australian market and introduce new strategies to encourage more Australians to drink better wine more frequently while still observing sensible and moderate consumption patterns.”

In developing the strategic responses (tactics) for the report, Wine Australia identified three megatrends and eight inter-related sub-trends, which it believes will influence consumer buying behaviours.


They followed this with a brand segementation strategy based around four levels or “personalities” for Australian wine. The four personalities - Brand Champions, Regional Heroes, Generation Next and Landmark Australia – equate to four value creations respectively: accessibility, interest, innovation and aspiration.

The segmentation strategy is followed by a number of strategic responses, some of which require further elaboration and some of which DIFFUSION believes are unlikely to change perception in overseas markets.

These include the development of a Wine Australia Trust Mark , a global communication plan and changes to to the exiting Wine Australia web site to better target user groups as well a brand health check to continually research and measurement of consumer perceptions of brand/country (Wine Australia) in key markets.

While the responses only address one of the directions in the paper and in themselves are unable to achieve both the desired repositioning and opening up of new markets for “fine” or premium Australian wine. What’s refreshing is that Wine Australia at least understands and acknowledges the importance of global brand propositions and positioning, something similar Australian government strategy papers have failed to understand (think Wool Australia or anything in ICT).

On the ground and particularly in lucrative US market, fine Australian wine lacks any great penetration.

The US market tends to operate as a multiple market. Step into any liquor store in New York and try and find a premium Australian wine. Sure you get Casella and a host of renamed Australian wines but it’s rare to find anything outside of the specialist wine stores. It’s a similar case in the UK, where Australian wine’s dominate the market but not at the premium end.

Firstly, the brand check should come first. Any one who understands the importance of brand will acknowledge this as should brand tracking and real research be a constant part of any good brand strategy. So many organisations and business shy away from real tracking or put this in the hands of their ad agencies.

Any communications strategy then should focus on making sure that the tactical responses (and they are tactical) are going to achieve the desired targets and are not something that came through an ideation workshop run by an agency.

So a Wine Australia trust mark is an interesting concept but it needs to get around the diminution of Australian wines by companies like South Corp, Beringer Bass and Fosters. Australian wines, regardless of what part of the market they have been developed for, already enjoy high trust status ..it’s just that there is no real brand recognition for labels called “Two Sheds”.

Similarly, redeveloping the Wine Australia website has to also go hand in hand with some real ecommerce initiatives mainly around tracking wine brands and enabling greater accessibility and visibility to the small regional labels and the landmark wines the paper identifies as part of the strategy.

What’s important about the Wine Australia directions paper is that it is so forward looking about the idea of strategic brand marketing. It's good news for marketers and brand agencies and that in itself is a rare drop.

Commbank takes its brand offshore.


In a move not reminiscent of the Coles Group (see DIFFUSIONblog 4 September 06: Is McCann set to give Coles a Walmart?) Australia's Commonwealth Bank has abandoned the creative work of its traditional Australian agencies and moved to US west coast agency, Goody Silverstein.

The move, reported this week in the Sydney Morning Herald, is certain to raise the hackles of incumbents STW and probably most other agencies in Australia.

More interestingly was the Herald columnists' assertion that "Australian companies (spell A_D_V_E_R_T_I_S_I_N_G) have for so long lacked any imagination or will to back interesting and engaging advertising and the ability of the communications sector to propose anything marginally outside of the predictable is remote."

Certainly that's been DIFFUSION's recent experience of adland as it seeks to perpetuate a mythic status as marginal thinkers and strategists. In fact, what we have seen is that most agencies seem content to rest on poor stale concepts and ideas and will not look for people outside the industry to change this. So, who can blame Commbank?

Just ask Optus, Singtel's Australian telecomms arm. There about to do the same thing to their Australian agencies for much the same reason. M and C Saatchi is likely to get the shove, and not without reason. Optus' "animals" were being used when I worked for Cable and Wireless in London, which dates from the time when Optus was owned by the former global carrier. So perhaps they need to be looking further afield or agencies in Australia need to work a lot harder?

The SMH doesn't let matters rest there. They put the boot in, describing senior marketing staff in Australia as "creatively retarded marketing managers". There's something in that as the dearth of great creative and well thought out brand strategy in this country is much the fault of clients as it is of agencies. Have a good look around at how they recruit senior marketing appointments. It's all through, in most cases, headhunters who work to set formulas and like their clients, rarely go outside the "predictable".

You reap what you sew.

30 April 2007

Is Australian Fashion Week and Rosemount on the same catwalk?


This year naming rights for Australian Fashion Week have gone to Rosemount Estate Wines, but is there might be a perceived misalignment between the two brands.

With Mercedes surrendering rights to Rosemount, DIFFUSION would have thought that there would have been a natural synergy between the brands as there was with its predecessor's long association.

Sure, Rosemount positions itself in the US and other markets as "The Prestige Wine of Australia" or so it's 2006 website proclaims and Australian Fashion Week, under the aegis of Simon Lock and now IMG, has successfully grown a new fashion event brand in a highly competitive but small market.

But anyone taking a trip down to their local liquor store or bottle shop will see that the "Prestige Wine of Australia" sells for less than $10 in its country of origin.

While for some this might indicate a high level of accessibility for a great wine, "prestige" and low prices seem somewhat incongruous with an international event that has helped launched the careers of such notable Australian designers as Colette Dinnigan, Akira Isogawa, Sass and Bide and Tsubi/Ksubi.

Rosemount might be repositioning, and this is understandably a long process that requires years of work, but the Fosters' owned brand also needs to translate its brand and marketing efforts to the product side, particularly in the Australian market. Sponsorships and naming rights are usually local affairs and work best when there is a perceived and actual alignment between the brand and the sponsor, not when it's merely exercising a proposition and a tagline. Even Rosemount's website makes no mention of Australian Fashion Week, an embarrassing oversight and yet another indication that the brand doesn't appear to have its brand and marketing act together in Australia.

Locally any brand that can offer itself to consumers at a range of price points below $10 (Rosemount's Diamond Range) and up to $30 for it's sparkling is not really competing with the likes of Grange or Giaconda or estates like Cape Mentelle, Domaine Chandon or Cullen.

For IMG and Australian Fashion Week, it will need to work harder to convince people that their names are synonymous, particularly as Mercedes remains a sponsor for other international events, particularly in the US. There's no details on the monetary cost of naming rights for the even but it's obviously a lucrative arrangement as the cost of showing skyrockets and major fashion names decline to appear.

Hopefully, Australian Fashion Week invitees will be supping on some of Rosemount's more pricier vintages.

14 April 2007

Prada goes mobile.


In its latest move designed to enhance its premium portfolio, South Korean electronics company LG and Italian fashion company Prada launched their a high-end luxury handset this week.

Not to be outdone by US competitor Motorola and D&G’s take on the Razr, LG's Prada mobile phone is claimed to be designed in close co-operation with the Prada design team, with both companies teaming up to distribute and market the new handset.

The phone is really a rebadged LG KE850 model but is now officially named the Prada Phone by LG. It supports EDGE connectivity and features a fully touch screen technology, enabling advanced touch interface as well as unique pre-loaded ring tones and content. Priced at around 600 euro, the Prada handset will initially be available in the UK, Germany, France and Italy, with Asian countries to follow. There is no date for either a US or Australian launch.

DIFFUSION doesn't think the Prada phone is designed to take on Vertu’s section of the market in what is a much more differentiated offer. What’s more interesting is LG's claims that Apple swiped the cool design and buttonless features, innovations included in the iPhone, set to launch in the US in June and likely to leave most of the mobile market in its wake. In our mind the Apple and Prada brands are much more aligned by attributes such as design, style and innovation than LG. The Prada phone is at a higher price point than the Apple, though it's likely they will share similar customers. And there is also no indication of what Prada is actually bundling with the new phone (store finders?). Maybe its just content with giving it a lovely Prada gloss.

04 April 2007

Google challenges TV advertising's black art.


Google's breaking into the world of television advertising sales with a new targetted model.

Launched this week in this US, Google's TV Ads enables TV advertisers to bid for spots to more than 13 million households on US satellite TV network Echostar and only pay for what is watched.

It's a major new foray into the world's more lucrative $170 billion television advertising market, after the company's recent failed attempts to launch it's Ad Sense model into print and radio.

However, at this stage the new ad sale system won't get quite as personal as its online counterpart because of US privacy restrictions.

The system will be targeted more broadly at specific demographic groups, regions and programs on one of EchoStar Dish Network's 125 satellite channels which include Discovery, CNN and MTV.

Google will be able to do a daily analysis of anonymous data collected from Dish network subscribers and only bill advertisers for that segment of an audience that actually watched a commercial for a designated amount of time.

Former NBC executive Mike Steib, who recently joined Google as head of television advertising, said that the group was already “in active discussions” with other networks.

However, Google is also likely to meet with stiff resistance from bigger US cable TV operators like Comcast, Time Warner Cable or Cox Communications, who jealously guard the data their systems generate on customer-viewing habits.

It also must face off against ad measurement competitors like Nielsen Media Research and hot start-ups like Spot Runner.

Either way, DIFFUSION believes that if Google creates the same impact it has had on the world of online advertising effectiveness its also going to have a sudden and very measurable impact on the way TV ads are sold.

More importantly, the black art of television advertising will come under even more scrutiny from advertisers, as they start to demand their agencies provide real-time measurement of active viewers and results from campaigns.

It's yet another signal for the death knell of television advertising as we know it.

26 March 2007

Coles breakup signals strategy failure.


Putting paid to his much vaunted big-box brand strategy, Coles Group Chairman Rick Allert announced today the troubled retail giant will be split and expressions of interest sought.

Despite a number 30 ranking in the global retailing stakes, Allert and CEO John Fletcher seems to have cast aside the dubious brand work of both McCann Erickson and Futurebrand and has told investors and the market that it was inviting expressions of interest for 100% ownership of the group including what they call the Everyday Needs Business (Coles Supermarkets and Kmart), Target and/or Officeworks. He also said the Group would also consider the sale of a considerable stake in the Everyday Needs Business as well as a demerger of both of Target and OfficeWorks.

Here at DIFFUSION we've been a long time critic of the group's less than comprehensible brand strategy, with Allert and Fletcher being consistently wrong footed by Woolworths. Just over three years ago Fletcher had the opportunity to set things right but even then he was saying his organisation didn't need one. It's about time other similar companies (we have a list!) woke up to the need for CEO-led wholistic brand strategy not run by their marketing departments or their advertising agencies.

Coles failure is a patent example of such strategy absence.

18 March 2007

BP tries a new shade of green.


In yet another case of corporates looking to control selected colour shades, global energy group BP has applied to the Australian High Court to secure the colour green.

Like our previous blog on Cadbury Cadbury sees red, not purple,28 April 2006 the move is the latest in the company's long running (and expensive) campaign to register the Pantone colour 348C as a trademark.

BP's new application comes in the wake of a Federal Court defeat in 2006, when the company's application to register the colour failed, overturning a previous trademark ruling that allowed the company to trademark the colour for use on its service stations and facilities. Interestingly the action was brought by Woolworths, who also use the colour greeen in their branding.

According to IP Australia, a company can own a colour if it can convince the Trade Mark Office that the colour is a distinctive aspect of its product. So while BP may call 348C BP green, having selected the shade in 1989 as the predominant colour for its service stations, the cull Federal Court in Australia wasn't convinced. It was most recently included in the revamped corporate identity.

Here at DIFFUSION most of us know that brand strategy and corporate identities in Australia built around a single colour are difficult to register. The case being that BP would have had to use the colour green alone within it's corporate identity. While BP's brand values might be founded on the idea of being green, it's corporate identity is awash with a combination of green and yellow, and thus the court saw green as only one part of the total brand identity. Further, the Court was not prepared to divide BP’s trademark into various applications to allow registration for the single colour. They ruled that the colour green by itself failed to acquire a secondary meaning and by that had not established consumer's were capable of distinguishing and recognising BP’s activities and brand from those of its competitors through the use of the colour.

Here at DIFFUSION, we wonder if in fact Pantone actually have ownership of 348C not BP. We may not be IP lawyers, but this statement from Pantone seems to contradict some of BP's claims:

...published materials of Pantone, are protected by copyright laws and include, for example, graphic presentations, color references, PANTONE Colors, PANTONE Names, numbers, formulas and software.


Pantone may not lay claim to the actual shade but they do to the registration and naming of it.

No date has been set for a hearing in the High Court.

16 March 2007

Stella McCartney gives Target some relief from cultural cringe.


Target, the Coles Group owned version of their American counterpart, have finally gotten a little design-savvy with the launch this week of internationally renowned designer Stella McCartney's winter collection.

The McCartney collection is part of a project, called "Designers for Target, style by design'' which has previously featured collections from Australian designers Melbourne's T.L. Wood and Sydney-based Alice McCall and Tina Kalivas. Unlike Target USA, this is a one-off project which illustrates some of the problems associated with the hero branding exercises like this.

Target USA are more design focussed than Australia with designers like Alessi's Michael Graves, Reidel and Isaac Mizrahi always in stock. The latest Target "Design for All" includes entire women's collections (not 14 pieces from Stella's atelier) by famed New York designers Proenza Schouler.

So why should we feel lucky we get this collection from Stella McCartney? After all she's been designing for Puma recently and the collection has been heavily featured in David Jones. And why is it only Qantas First and Business class passengers will get the benefits of design supervision by Australians Mark Newson and toiletries courtesy of Akira Isogawa and Colette Dinnigan? It all smacks a little of the old Australian cultural cringe. It's only acceptable for most people if its an overseas designer and has a premium attached to it. Here at DIFFUSION we believe good design should always be cheap and accessible. The Coles Group has had the opportunity to do this for a long time now. So let's see something from the likes of Akira, Colette and even Stella EVERY time we visit a Target Store.

Can BlueFreeway survive the Web 2?


Here at DIFFUSION we all witnessed the meteoric rise and soporific fall of digital agencies during the late 90s. Indeed, we were there in London and New York when they tried to recruit us to their agencies. The list is long and the names mostly forgettable: Scient, Viant, Deepend, Zentropy, Monday, Razorfish, Digitas, Lante, USWeb, CKS, Spray, China DotCom. Even in Australia, the likes of Attik, Spike, Deepend, MarchFirst, Razorfish all came and went with only smaller agencies and the larger integration houses surviving. So why is BlueFreeway going to be any different?

Their model is similar to those of companies like the Nasdaq-listed aQuantive, who acquired the Razorfish in 2004 and now works with leading brands to build large-scale websites and the digital marketing programs that drive traffic to them. Like BlueFreeway, aQuantive is an aggregator of digital design, marketing, performance and advertising services and has been busily acquisitive with no less than 12 companies in its portfolio spread from Avenue A/Razorfish in New York to Amnesia in Sydney. Like BlueFreeway, they range in size and market footprint.

Last week the ASX-listed BlueFreeway announced a combined profit growth of 27% across its group of companies for the six month period ending December 2006. While it was great news for those who managed to get shares in the oversubscribed float, the sustainability of the model is still under question. The results were unaudited and excludes costs associated with the Destra, which are already attacking the bottom line. Most of the agencies in the BlueFreeway group are small and perhaps with the exception of Spin and hosting company Destra, subject to the same kinds of market vagaries and pursuit of the unknown that killed so many of the more pioneering aggregation plays in the late 90s. More interestingly, like aQantive, the challenge will be see if this model can really make the kind of impact that CEO Richard Webb was able to with his former company RedSheriff. Or does Web 2 leave companies founded on old notions of how to build revenues (the traditional agency/service model) floundering?

05 March 2007

Is Starbucks on the nose?


According to a weekend report in the Washington Post, Starbucks Chairman Howard Schultz believes his stores have lost their soul. Or is he really talking about their brand essence? (see our blog 20 October 2005 The defining essence. Getting a handle on Oroton)

Quoting a leaked internal memo to his CEO and other executives, the Post reported that Schultz believes his 13,000 stores worldwide stores no longer even smell like coffee because of "flavor locked packaging".

But now the chairman of the world's leading coffee retailer seems to be onto something that should have occurred to him long ago, describing how "some people even call our stores sterile, cookie cutter." In the 14 February memo entitled "The Commoditization of the Starbucks experience", Schultz laments the the loss of "the romance and theatre" of the traditional Italian espresso machines, which have been replaced by automatic machines (in this Starbucks are not alone). Schultz wrote that the new efficient machines now commonly used in the stores block customers from watching as coffee is made and sharing what he called an "intimate experience with the barista." He obviously hasn't really visited a store recently if he thinks his staff can really be described as "baristas", when anyone who has worked their knows that a real barista does not simply press a button.

But to give Schultz his due, he is very aware of the threat from competitors who have created a more authentic coffee experience (anyone who's every bought the freshly grounf from Toby's Coffee in Sydney's Wooloomooloo would know this). Though likening them to pests who need to be "eradicated" seems to a touch colourful. More importantly, Schultz doesn't really suggest any alternatives given the scale and scope of the problme.

Here at DIFFUSION, we think it might be a good idea if the Starbucks's chairman think more carefully about how the stores could better reflect their local communities, how they might build a genuine rather than simply a differentiated brand experience and not rely solely on technologies and store layouts to maximise ROI. After all they have had to have been doing something right building the brand for the past 20 years, they must have learnt something.

A full transcript of the memo can be found at Starbucks Gossip http://starbucksgossip.typepad.com/_/2007/02/starbucks_chair_2.html
It reads:

From: Howard Schultz
Sent: Wednesday, February 14, 2007 10:39 AM Pacific Standard Time
To: Jim Donald
Cc: Anne Saunders; Dave Pace; Dorothy Kim; Gerry Lopez; Jim Alling; Ken Lombard; Martin Coles; Michael Casey; Michelle Gass; Paula Boggs; Sandra Taylor

Subject: The Commoditization of the Starbucks Experience

As you prepare for the FY 08 strategic planning process, I want to share some of my thoughts with you.

Over the past ten years, in order to achieve the growth, development, and scale necessary to go from less than 1,000 stores to 13,000 stores and beyond, we have had to make a series of decisions that, in retrospect, have lead to the watering down of the Starbucks experience, and, what some might call the commoditization of our brand.

Many of these decisions were probably right at the time, and on their own merit would not have created the dilution of the experience; but in this case, the sum is much greater and, unfortunately, much more damaging than the individual pieces. For example, when we went to automatic espresso machines, we solved a major problem in terms of speed of service and efficiency. At the same time, we overlooked the fact that we would remove much of the romance and theatre that was in play with the use of the La Marzocca machines. This specific decision became even more damaging when the height of the machines, which are now in thousands of stores, blocked the visual sight line the customer previously had to watch the drink being made, and for the intimate experience with the barista. This, coupled with the need for fresh roasted coffee in every North America city and every international market, moved us toward the decision and the need for flavor locked packaging. Again, the right decision at the right time, and once again I believe we overlooked the cause and the affect of flavor lock in our stores. We achieved fresh roasted bagged coffee, but at what cost? The loss of aroma -- perhaps the most powerful non-verbal signal we had in our stores; the loss of our people scooping fresh coffee from the bins and grinding it fresh in front of the customer, and once again stripping the store of tradition and our heritage? Then we moved to store design. Clearly we have had to streamline store design to gain efficiencies of scale and to make sure we had the ROI on sales to investment ratios that would satisfy the financial side of our business. However, one of the results has been stores that no longer have the soul of the past and reflect a chain of stores vs. the warm feeling of a neighborhood store. Some people even call our stores sterile, cookie cutter, no longer reflecting the passion our partners feel about our coffee. In fact, I am not sure people today even know we are roasting coffee. You certainly can't get the message from being in our stores. The merchandise, more art than science, is far removed from being the merchant that I believe we can be and certainly at a minimum should support the foundation of our coffee heritage. Some stores don't have coffee grinders, French presses from Bodum, or even coffee filters.

Now that I have provided you with a list of some of the underlying issues that I believe we need to solve, let me say at the outset that we have all been part of these decisions. I take full responsibility myself, but we desperately need to look into the mirror and realize it's time to get back to the core and make the changes necessary to evoke the heritage, the tradition, and the passion that we all have for the true Starbucks experience. While the current state of affairs for the most part is self induced, that has lead to competitors of all kinds, small and large coffee companies, fast food operators, and mom and pops, to position themselves in a way that creates awareness, trial and loyalty of people who previously have been Starbucks customers. This must be eradicated.

I have said for 20 years that our success is not an entitlement and now it's proving to be a reality. Let's be smarter about how we are spending our time, money and resources. Let's get back to the core. Push for innovation and do the things necessary to once again differentiate Starbucks from all others. We source and buy the highest quality coffee. We have built the most trusted brand in coffee in the world, and we have an enormous responsibility to both the people who have come before us and the 150,000 partners and their families who are relying on our stewardship.

Finally, I would like to acknowledge all that you do for Starbucks. Without your passion and commitment, we would not be where we are today.

Onward…


.

25 February 2007

Coles brand backflips.


As DIFFUSION predicted (Is McCann set to give Coles a Walmart 9/4/06) Coles Group's roll out of it's new brand strategy is proving problematic.

Firstly, the much heralded closure of the Bi-Lo brand has not resulted in customers flocking to Coles supermarkets, as was hoped, but to competitors like Woolworths, Aldi and those pesky IGA stores. What this is likely to mean is that its other brands (K-Mart, Vintage Cellars) in the portfolio also slated for the chop are likely to be left standing while John Fletcher and those masterminds at McCann Erickson and Futurebrand rethink the much vaunted supercentre approach. Yes, supercentre is what they are going to be called. Just check out a recent National Retail Manager role Cole Group advertised two weeks ago describing the Coles Supacentre as "radically transforming the retail experience in Australia".

Secondly, there's the tiny issue of an imminent-any-time-any-day-now-soon sale after Fletcher and Coles Group Board chairman Rick Allert decided to throw in the towel and succomb to the inevitable private equity tsunami engulfing some large underperforming listed companies throughout Australia.

Thirdly, Coles Group's current lacklustre trading performance is putting even more pressure on Fletcher and Co to get the new strategy right. Here at DIFFUSION we've received word from Tooronga that there's quite a lot of internal dissatisfaction with the new direction. Insiders are wondering whether the new strategy is going to work.

In the end, it might all be for nought. If, after an equity group breaks it up and Woolworths nabs Coles' best performers Target and OfficeWorks, what will they be left? An underperforming supermarket chain and a lacklustre variety store. Hardly the stuff of dreams.

09 November 2006

The politics of attack advertising.


According to the definition by the US Centre for Media and Democracy in it’s SourceWatch www.sourcewatch.org/, an attack advertisement is a short, 15-60 second piece of political advertising usually on the electronic media and almost always aired during an electoral campaign, but maybe as a third party ad. It is a key feature of negative advertising and is often used to discredit a political figure or message. An attack ad is negative advertising but it also consitutes a new form of advertising, using some of the elements found in propaganda.

The most recent examples are those which have been used by both parties and independents during the recent mid-term elections in the United States and in Australia by the Labour Party, as part of an advertising campaign criticising Prime Minister John Howard’s trustworthiness and honesty over interest rates. There is also some talk attack advertising will be a feature of some of next year's State elections in Australia by the Labour Party.

The current campaign features billboards and commercials which portray John Howard as Pinocchio (see picture), whose nose has grown longer with each of the past seven interest rate rises. The campaign mocks his 2004 election pledge "to keep interest rates at record lows" and asks: "Who do you trust now?"

Common features of such an attack ad include conceptual metaphors that can serve to smear opponents (hence John Howard as Pinocchio), memorable sound bites intended to be repeated by the public on the street and in discussions about how to vote and to avoid libel claims, using deliberate ambiguity, fatuous and extreme assertions, which go beyond legal liability

All of this can also be delivered with a degree of humour.

So if the attack ad fails, an attack ad campaign can be "spun" into "good fun" by simply extending the conceptual metaphors or extreme assertions to humorous lengths.

Attack ads utilise a variety of familiar propaganda techniques to influence opinions. Attack ads may be presented through a variety of broadcast or print sources but usually are intended to deliver a specific message to a select audience. Rather than support a position held by the advertiser, attack messages target an opponent's platform, track record, background or character.

But for an attack ad to be really effective, the message probably needs to be believable. Repulsive imagery conveyed in attack ads might reinforce allegations or mask outright character attacks. The ads often rely on the resonance of the message to attract the attention of target audience members to a message most other listeners or viewers will ignore.

Let’s judge later the effectiveness of current attack advertising after the US mid-terms and maybe even see if Australian Prime Minister John Howard starts to develop a credibility gap. But according to Wikipedia http://en.wikipedia.org/wiki/Attack_ad some believe that attack ads are useful in shaping public opinion with some analysts claiming the effects can be as great as five percent change. However, it’s a fine line if an attack ad may fail in its intended purpose and backfire against the group which first used it. For example, if an ad is seen as going too far or being too personal the voters will turn against the party that put out the ad. There will be examples of this to be found in the mid-terms.

In the US, research has consistently found that negative advertising has positive effects. Finkel and Greer (1998) said negative advertising “is likely to stimulate voters by increasing the degree to which they care about the election’s outcome or by increasing ties to their party’s nominee.” This is an important feature of negative campaign advertising because it can solidify a candidate's support going into an election. The finding was repeated by Goldstein and Freedman (2002), who found that negative campaign ads raise interest in the election as well as raise the perceived importance of the election, which increases voter turnout (an important factor in non-compulsory US voting).

Here at DIFFUSION we don’t expect attack advertising to remain the sole property of political parties and their advertising agencies or even of political campaigners. What we see is the wider application of attack advertising into more general fields, designed to attack competitors or to dispute product or service claims. Either way, the ground has been established for their use and their effectiveness to mobilise a purchase decision has been proven.

04 September 2006

Heinz HP sauce goes dutch.


One of Britain’s most iconic sauce brands is likely to become another victim of a point of origin fraud with company owners Heinz announcing the brand is going to be made by the Dutch.

HP brown sauce (yes, we even have it in Australia) famously features the Houses of Parliament on its label and the announcement last month that it US parent Heinz wants to close its plant in Birmingham and move production to Holland has sent shockwaves through Britain. The sauce has been made in Birmingham for 103 years and the move will likely result in the loss of both jobs and the brand's most favoured status as the UK parliament’s brown sauce of choice.

Even more interesting is the proposal by rivals Branston to consider adopting the same symbol on their own Branston brown sauce bottle. Heinz' move has sparked off another round of hand wringing by the British about the importance of “Britishness” and point of origin as an emotional and pivotal part of culture.

Here at DIFFUSION we’re both defenders of point of origin and truth in labelling as important elements of brand heritage (see blog 7 February 2006 Points of Origin)

Is McCann set to give Coles a Walmart?


Why is that when a company has a weak or non-existent brand strategy they try and fix it with advertising?

Coles seems to be desperately trying to bolster what is widely regarded by the market as a flimsy brand strategy, by drafting the help of senior New York McCann Erickson advertising executives, according to the Sydney Morning Herald last week.

McCanns' is working alongside their Interpublic Group stablemates, FutureBrand, on a reported combined monthly fee of $750,000 and the team includes some Walmart account veterans - so we think we know where this is going. Coles had previously only made a few quiet asides about FutureBrand's involvement in the rebranding, unveiled at its much maligned strategy presentation at the end of August.

DIFFUSION thinks maybe the reticence by Coles Group chief executive, John Fletcher, to provide more details on the strategy was because it hadn’t really been worked out. Now that McCanns' have weighed in, it’s likely any strategy will be one led by massive brand advertising rather than the much needed fundamental brand analysis.

Yet there’s going to be a lot more work to be done on the proposed “everyday needs" monolith before Coles puts it in front of shareholders at the next presentation in November. The Coles Express, First Choice, Liquorland, Vintage Cellars, Kmart and Theo's Liquor names are all set to be axed for the single disingenuously named brand.

We’re still scratching our heads about the decision to axe both Express and Vintage Cellar brands. Express has been the bulwark for Coles' hugely successful foray into forecourt marketing and with the sale of Myer, Vintage was the only premium brand left in the portfolio with neither Target or OfficeWorks filling that space. It’s all down market from here; which leads us to ponder...

While Walmart's business model, as the 'king' of low prices, makes it the envy of retailers around the world model, DIFFUSION hopes Coles will not be following in its path. Consistently ranked in the top 10 of most crisis prone organisations in the US, Walmart's human resource, social and environmental policies have left its public in uproar.

In addition, we believe that international trends (aside from the US who still seem to be locked into the bigger-brighter-better-is-best notion) are indicating a move away from monolithic brands towards portfolio brands, with which customers can build more intimate relationships; it's also a smarter risk management strategy - if one brand fails, it will not affect the rest of the portfolio.

The advice we hope McCann is giving Coles is culturally sensitive to how, and from whom, we want to purchase in Australia. They should acknowledge the mistakes monoliths such as Walmart have made and base the new strategy on international best practice that is simply not US-centric.

18 August 2006

Polo Ralph Lauren goes immersive.


We've been talking about it for some, well ever since THAT Tom Cruise movie...yes the 2002 blockbuster Minority Report...and it seems like we were not the only ones who thought that immersive marketing was not too far away. First Eyecorp (see blog 18 March 2005, 'Minority Vision') and now Ralph Lauren.

Polo Ralph Lauren have just launched a new interactive window in their Madison Avenue shop that allows shoppers to choose and purchase an outfit projected on the shop window, even when the store is shut.

“After watching Steven Spielberg’s Minority Report, I really wanted to find a way of making that amazing technology a retail reality. We are thrilled to offer such a unique and exciting way for our customers to further explore the world of Ralph Lauren; with this initiative we are reinventing the concept of shopping anytime” said David Lauren, Senior Vice President Advertising, Marketing and Corporate Communications of Polo Ralph Lauren.

It's a classic case of life imitating art.

04 August 2006

Coles tries on a new lite strategy.


On Monday 1 August the Australian supermarket giant Coles went public with the results of their eagerly awaited nine month internal review. They were greeted by a lukewarm market reception and bewilderment as to the scope and nature of their new brand strategy.

Coles CEO, John Fletcher, said the newly named 'Coles Group Limited' (as we predicted in our blog on 13 July 2006) complete with a bright curly cue logo would "drive sales and earnings growth by further simplifying its business to invest in stores and customers’ shopping experience" by focussing on "customers’ everyday shopping needs".

The most interesting part of the announcement was the decision to integrate the existing food, liquor, fuel and general merchandise businesses (Coles Supermarkets, Liquorland, Vintage Cellars, 1stChoice Liquor Superstore, Coles Express and KMart) into something vaguely called "everyday needs".

While the Sydney Morning Herald's coverage on the same day seemed to interpret this to mean that everything would be called "Coles", our understanding is that while the Coles name would feature prominently in the newly branded business, this is not necessarily the case...

In addition, we are not convinced that calling something "Coles Everyday Needs" is particularly evocative of anything. Perhaps really what they are trying to do is simplify the group structure so that the process of marketing, supply chain and management can be centralised and significant savings made by reducing head office numbers and duplication at various management levels of the existing brands.

Fletcher claims that the Group will be spending $60 million to improve the customer experience in supermarkets and increasing investment in Target and Officeworks, which they have chosen to retain. Yet, why announce such a large spend working on what is demonstrably a poor experience (which you will be inevitably looking to rebrand over the next two years)?

“We have spent the last nine months researching our customers, team members, suppliers and the world’s best retailers to ensure there is overlap between our current and next strategic direction,” Fletcher said in the company release.

This is a very strange claim when both DIFFUSION and most market analysts remarked that the Group lacked any real strategic direction.

“During this time it has become clear that two key themes – customer intimacy and simplification – will drive future growth, enabling us to direct additional resources and focus to engaging our customers with better service, more convenience, and better products and rewards.”

Similarly, Fletcher's claims that these two themes are the bulwark of any future growth are also odds with a culture that to date has seemed to shun any notion of better service by reducing the ratio of staff to customer numbers, defined 'convenience' by opening hours, marginalised suppliers by screwing ever better deals and increasing its reliance on own brand products (see our blog on 18 March 2005) and vastly diminished rewards for customers by increasing eligibility thresholds.

Fletcher is now working on the idea that the "key to the new everyday needs business will be the creation of a lean and innovative culture in which stores are ‘heroes’, and where team members are empowered to deliver great service and products to customers.”

Fletcher's description of the new stores in terms of both "innovative" and "heroes" seem a contradiction in terms. Under his stewardship, the Group's brands have been denuded of any real intrinsic value and supported by bland propositions. The "everyday needs" proposition is equally fraught. Will the new store formats that Coles will invest something like $850 million in, become hypermarkets, along the lines of Carrefour or WalMart?

We don't know the answer because Coles and Fletcher is still working out the details of what can only be described as a strategy that not only views brand as the sum of a capital spend but also takes for granted the notion that customers are more interested in logos and fascias, rather than details of how they might actually get better service.

31 July 2006

DIFFUSION talks brand at PRIA.

Discussion points from the 'Senior Practitioners' Cocktail Roundtable Event', 1 August 2006, Public Relations Institute of Australia.

DIFFUSION director Stephen Byrne discussed the importance of developing a brand strategy as a primary business requirement against the context of effective public relations and communication planning.

Brand strategy within business and communication planning

The idea of integrated communication, which holds that all communication emanates from a single strategic platform, has largely failed. A number of underlying currents have been largely responsible for this:

1. Agencies are constrained by their media bias
2. Business structures don't mirror integrated communication planning
3. Development is too far down the value chain to be effective, and
4. Brand strategy is silo-ised by being viewed as a marketing and communication activity

Most companies are focussed on action and tactics, rather than an actual brand or communication strategy. The need to demonstrate branding success through empirical evidence, often replaces planning. So a brand strategy, if it exists at all, becomes synonymous with a set of tactical communications developed by tactical specialists often working in isolation.

A holistic business strategy, with brand as an essential part of it, provides strategic intent which can help unite and integrate all communication activities - such as public relations, advertising, investor relations, interactive or internal communication.

Any brand strategy must begin with understanding the role of brand within the business model and determining how best brand can help grow and sustain the business. Brand strategies should engage the highest level of management because it brings strategy, finance, marketing and communication together, to manage the brand.

Towards a business brand strategy

Ten steps necessary to build a successful a brand–based communication program:

1. Understand, formally define and acknowledge brand in your business planning; have a formal brand strategy
2. Understand those factors that contribute to the creation of brand value
3. Identify and understand all your audiences
4. Define your point of difference and build value propositions around that
5. Work out how you can clearly enunciate your point of difference so that audiences understand it
6. Create messages
7. Identify and define the role of each medium in changing perceptions and sustaining communication momentum
8. Determine an appropriate communication mix
9. Only develop those communication activities that support brand
10. Review and revisit from 5.

Brand’s role in holistic business planning is an organic process. Always return to your strategy to check whether all the assumptions you have made are still valid and correct.

http://www.pria.com.au//events/id/227

20 July 2006

Is Coles still Myer for Xmas?


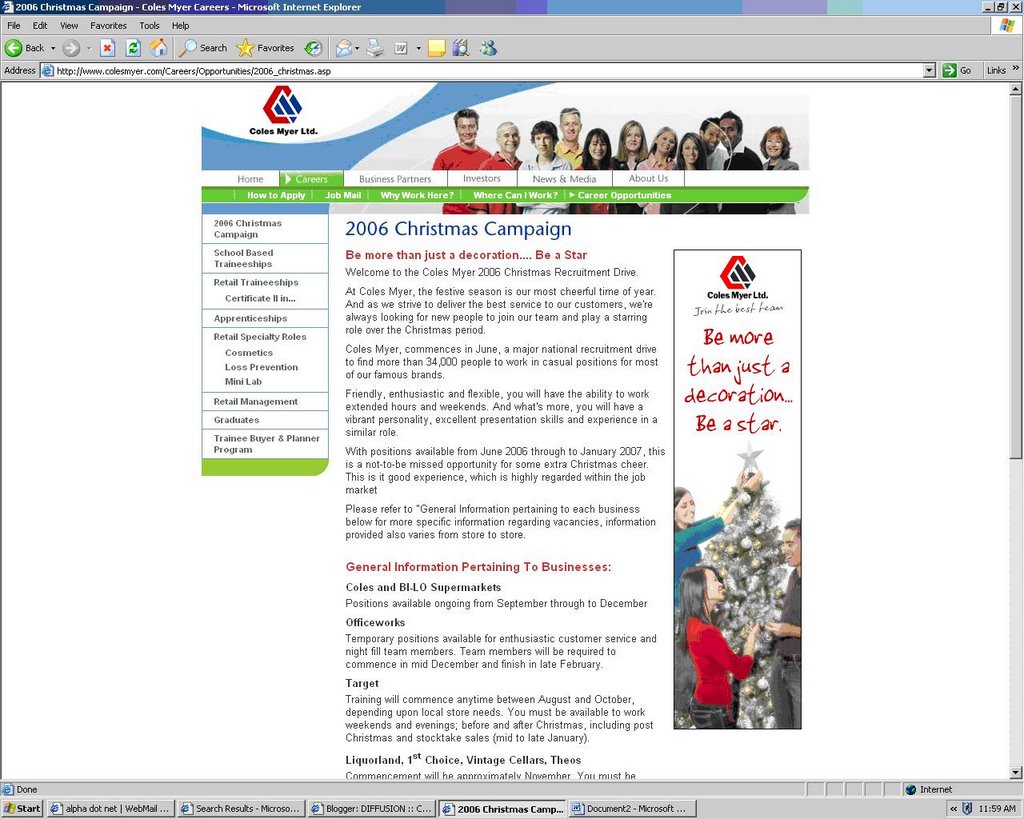
Picking up a bottle of wine in our local Vintage Cellars this week, DIFFUSION was interested to notice a flyer for casual positions available at Coles Myer brand stores during Christmas 2006. While we are not sure about the copy, “Be more than just a decoration…Be a star” (what exactly does this mean?) we were more interested to note the inclusion of the MYER logo on the flyer. Now we know that festive season recruitment starts early but with the confirmed sale of MYER happening in March, we'd like to think that by mid-July they might have had an opportunity to think about a reprint? That said it's nice to see Coles Myer with a new cleaner, brighter and more functional website (with not a MYER logo in sight)!