10 May 2007

IPTV, is it "better TV" or just "more TV"?


TV is dead, long live TV.

Certainly, that's the view of Microsoft founder Bill Gates, when he delivered the keynote address to Microsoft's yearly gathering of its advertising partners from around the world at the company's eighth annual Strategic Account Summit, early this month.

And strangely Gates might be right.

According to Nielsen Media Research what is called prime-time "viewership" for the four biggest broadcast US networks, fell from 40.3 million to 37.6 million people.

What this means is that people seem no longer beholden to network television to determine both the time, programs and place of viewing. Soon it will also be about the the media they use to view TV.

And Gates, who's been catching up on his more visionary outpourings ever since he missed the initial internet bubble, sees a new media landscape dominated by internet protocol TV (IPTV), where people will own single, high-performance wireless devices, download high definition television from anywhere in the world (but using Microsoft middleware) and viewing becomes more social and personalized.

The sorts of macro changes he predicts includes portable computing devices (we're thinking something not unlike Apple's iPhone with huge amounts of storable memory pluggable into home networks), which work anywhere and in any environment on any platform.

"We need to make things more user-centric", said Gates.

He thinks too much of digital media is designed on a per-device basis and he sees that changing, both in terms of the development of single devices that DIFFUSION believes can be used in all environments - home, office, play - as well as in all contexts while running on seamless various Web-based communication platforms.

Gates is obviously an avatar for IPTV, which Microsoft has made significant investments in. Microsoft is working with 16 customers in 15 countries on four continents around the world with nine of those customers commercially deploying IPTV services including AT&T U-verse, BT Vision, T-Home from Deutsche Telecom and Bluewin TV from SwissCom

"There's no way broadcast infrastructure over these next five years will not be viewed as competitive. The end-user experience, and the creativity, the new content that will emerge using the capabilities of this environment will be so much dramatically better, that broadcast TV will not be competitive, " he said.

"In this environment, the ads will be targeted, not just targeted to the neighborhood level, but targeted to the viewer. And more and more as the viewer is coming to a TV set, either through just choosing off a menu, or recognizing voice, or some video type thing, it will actually not just know the household that that viewing is taking place in, but will actually know who the viewers of that show are."

Microsoft demonstrated how IPTV worked at the presentation, including its capacity for virtual tuning, instantaneous recording of up to four programs from a digital EPG, true video on demand, high definition display and recording. They wrapped it in the moniker of "better TV".

Gates made similar bold predictions for the future of gaming, which is already seeing the Xbox combine with a set top box to enable new forms of social gaming.

So what will happen? When will we really see what Gates calls "better TV"?

Most people, in Australia and the rest of the world, still receive traditional broadcast TV. IPTV and on-demand video won’t change typical viewing behavior for some time (only because we're never going to get it real soon) but TV is changing and will continue to change, because the Internet is forcing it to. However, we're more likely to see a more cumulative change, as is being reported by Neilsen, rather than massive, dramatic change.

Certainly Australia hasn't been very exposed to the joy of TiVo and Foxtel's IQ is limited to subscribers and companies like ICTV has struggled, but programming, the product and carefully synced ad placement is something the networks in Australia have already started toying with.

However, three strands of broadcasting will emerge - traditional network broadcasting, subscription TV and narrowcasting using IPTV, the last we believe will become the most dominant. Companies like YouTube and Google Video will embrace IPTV and start to mimic traditional network programming in much the way Pay TV channels do but with more user centric programming. In addition, new companies like Vquence will provide the kinds of advertising solutions which allow narrowcasters to integrate real clickable advertising into programming.

Gates is right when he says that convergence is a key area driver for future television. IPTV will be broadcast across all types of devices but via a single platform (something he's hoping that XBox is a harbinger of). But it's also going to be influenced by digital rights management and the whole IP debate around content ownership. And that's a very fluid area right now, particularly on the heels of YouTube's capitulation to US content owners (the networks and studios). While we're not likely to see a repeat of Napster, we are likely to see IPTV circumventing the four/five channel monopolies in this country.

While there certainly is demand for IPTV services in Australia. In 2005 Australia, the second biggest group of TV downloaders in the world, was responsible for 15.6 per cent of illegal downloads of mainly US content.

But we're not likely to see a commercial IPTV platform in Australia until the kind of broadband networks with fibre to the node and in the home is a reality. And that seems to be what some of the argument between Telstra, the G9, the Australian Government and the ACCC is really about. The reality is we need to be able to get speeds up to 26 megabits per second, when most home systems run at 256 kilobits and therefore unable to support three high definition channels, VOD, VOIP and full internet access.

For the time being we're going to see viewers struggle along with video over the internet (JumpTV or iTunes, for example) and more makeshift offerings from Telstra and Foxtel, who initially promised IPTV in 2005. In the meantime, the traditional networks, both in the US and Australia, will continue to see the kinds of change Neilsen has begun to report.

07 May 2007

Prada at Kmart: luxury brands and status abandonment.


It's only a small thing. But as we all know small things can lead to big things.

But the release of a new Prada fragrance, Tendre (selling for $79.00) in the Sydney Mother's Day catalogue for Kmart Australia, certainly signals to DIFFUSION that Prada seems to be heading down the same road of luxury brand dilution that destroyed the once great Pierre Cardin, nearly brought down the house of Calvin Klein and which threatens so many brands in this market.

Sure you might argue that it's only perfume and for this brand a cheaply priced one at that, but the democratization of luxury brands seems to be destroying those aspects of a luxury brand (exclusivity, price, access, aeesthetic) that denote these brands.

It's fact we noted in our blog The Defining Essence 20 October 2005 and one that seems to have escaped Prada's owners as they take the brand into the mass luxury market.

Perhaps the Prada licensees haven't read the definition of luxury that in 2000 the European Commission used to review Prada's role in the market as part of a ruling on it and LVMH's acquisition of Fendi. What's important about this ruling is that it is one of the few non-academic reviews of the operation of luxury goods.

The Commission described "luxury products" as "high quality articles with a relatively high price, marketed under a prestige trademark". As such luxury goods were considered to operate in a single product market because of two factors "substitutability from the demand side: the idea of acquiring a luxury good is linked to prestige rather than consumption of a precise item" and "substitutability from the supply side" or where most of the producers of luxury goods manufacture a broad range of products such as ready to wear, leather goods, fashion or, in this case, perfume.

This definition fits in comfortably with our understanding of both the pricing and accessibility attributes of luxury brands. More importantly, the definition attaches the generally accepted idea that prestige is also linked to acquisition and not the actual consumption of the item. Which is probably to say that a lot of women will see the Kmart catalogue and think "I have to have this Prada perfume because it is a such a luxe brand".

What's also interesting from this ruling is the Commission also connects both the transactive distance of luxury brands and the aesthetic of their environmental setting to their definition, noting that Prada itself indicated that "the common denominator is the importance of qualitative requirements designed to maintain the image of prestige, exclusivity and the high quality of the brand (e.g. location, the nature of the external appearance of neighbouring shops, decoration and fittings of the outlet which should reflect the prestige of the brand)."

This hardly sits well with my knowledge of my local Kmart located in a suburban shopping mall which hosts a Baker's' Delight, Go-lo and a Wendys and where Prada perfume is likely to sit alongside the latest offering from Paris Hilton in aisle six.

So, by their own definition Prada not only seem to be falling out of the luxury goods market in their attempts to market mass luxury but also are defying some of the basic principles of luxury brand management. These are:

1. creating distance, a no-mix area or barriers to entry for those who are not invited and by necessity of protecting clients from non-clients;

2. selective pricing and and exclusive distribution as well as the aesthetic dimension of the products; and,

3. the recognition and acknowledgement of its luxury status by all.

By all three counts Prada is failing. First, by not maintaining and enforcing these barriers to entry and allowing their licensee to flout it. Second, by using a selective pricing model more recognisable as that of a democratic, basic brand model (other brands of perfume can sell at Kmart at similar prices) and finally, there appears to be both an acknowledgement of its luxury status by very inclusion on the front page of the catalogue, and also an argument for a case of status abandonment by Prada's Australian licensee and, I suspect, its international license holders, for this latest distribution deal. I'm sure it won't be first such breach.

03 May 2007

Ford and Rip Curl go beyond the wave.


Is Ford’s Ripcurl XR8 Ute Australia’s first co-branded car? It could be. Already a co-sponsor of a major Australian surfing title, the US manufacturer is doing some serious stretching in Australia alongside surfboard and clothing company Rip Curl.

While car manufacturers can piggyback on a large, loyal and extremely well profiled audience (think Ford vs General Motors Holden), it might also work if only to a niche market.

Hitching up with an existing youth brand seems like a good idea, especially if it’s an iconic Australian surf sport brand, like Rip Curl. And co-branding is useful as it helps reinforce the lifestyle image of the cars (how Australian is a ute after all, unless it's a panel van?) by linking in to an existing group of customers with similar tastes, lifestyle, or age. So it must be something that Ford has been missing out on as it seeks to bolster sales in a flagging demographic with the tie-in.

But it’s not Ford’s first foray into co-branding arrangements with clothing companies. Ford USA already produces SUV’s with lifestyle and clothing retailer Eddie Bauer (there’s a range of two and 4WDs in the 2007 series) and Subaru has teamed up with US outdoor clothing catalogue company L.L. Bean to produce the Subaru Gear range of outdoor apparel.

And there’s similar examples of between sports shoe and sports vehicle think Porsche and Puma, Adidas and Porsche, Ducati and Adidas, but mostly it’s been one way co-branding.

The most important thing for Ford is to make sure that the brand association works both ways, so that the target market segments don’t start to see it a just another multinational muscling in on a cool brand. Beyond the Rip Curl extras, what really makes this is a true Ford brand experience? What preserves brand attributes?

Importantly for Rip Curl, they should be wary that there is no diminution of their own brand by the target segment (as seen in the current Australian television advertising) but also by future target segments and this will require some strong brand management.

Australian wine is a glass half full.


Australia’s wine industry recognises it's glass is half full and now wants to reposition Australian wine at the premium end of the market.

This week the Australian Wine and Brandy Corporation and the Winemakers Federation of Australia unveiled their Wine Australia: Directions to 2025. The Directions paper, which in a rare case of both industry cooperation and speed of report writing, was commissioned in 2006 and recommends 46 directions to be adopted by winemakers and marketers in coming months.

According to the report, Australia’s wine industry must” focus on strengthening sector structures, directly influencing domestic and export markets and gearing up for sustainable success.”

“The Australian wine sector needs to re-evaluate its current approach towards export markets. It needs to identify new and sustainable market opportunities through detailed market intelligence, and turn consumer interest into aspiration through segmented marketing strategies. In particular, this only can be achieved by raising awareness and expectation of an Australian wine story founded on an international reputation for regionally distinct and fine wine production. Further, it also needs to refocus its expectations in the domestic Australian market and introduce new strategies to encourage more Australians to drink better wine more frequently while still observing sensible and moderate consumption patterns.”

In developing the strategic responses (tactics) for the report, Wine Australia identified three megatrends and eight inter-related sub-trends, which it believes will influence consumer buying behaviours.


They followed this with a brand segementation strategy based around four levels or “personalities” for Australian wine. The four personalities - Brand Champions, Regional Heroes, Generation Next and Landmark Australia – equate to four value creations respectively: accessibility, interest, innovation and aspiration.

The segmentation strategy is followed by a number of strategic responses, some of which require further elaboration and some of which DIFFUSION believes are unlikely to change perception in overseas markets.

These include the development of a Wine Australia Trust Mark , a global communication plan and changes to to the exiting Wine Australia web site to better target user groups as well a brand health check to continually research and measurement of consumer perceptions of brand/country (Wine Australia) in key markets.

While the responses only address one of the directions in the paper and in themselves are unable to achieve both the desired repositioning and opening up of new markets for “fine” or premium Australian wine. What’s refreshing is that Wine Australia at least understands and acknowledges the importance of global brand propositions and positioning, something similar Australian government strategy papers have failed to understand (think Wool Australia or anything in ICT).

On the ground and particularly in lucrative US market, fine Australian wine lacks any great penetration.

The US market tends to operate as a multiple market. Step into any liquor store in New York and try and find a premium Australian wine. Sure you get Casella and a host of renamed Australian wines but it’s rare to find anything outside of the specialist wine stores. It’s a similar case in the UK, where Australian wine’s dominate the market but not at the premium end.

Firstly, the brand check should come first. Any one who understands the importance of brand will acknowledge this as should brand tracking and real research be a constant part of any good brand strategy. So many organisations and business shy away from real tracking or put this in the hands of their ad agencies.

Any communications strategy then should focus on making sure that the tactical responses (and they are tactical) are going to achieve the desired targets and are not something that came through an ideation workshop run by an agency.

So a Wine Australia trust mark is an interesting concept but it needs to get around the diminution of Australian wines by companies like South Corp, Beringer Bass and Fosters. Australian wines, regardless of what part of the market they have been developed for, already enjoy high trust status ..it’s just that there is no real brand recognition for labels called “Two Sheds”.

Similarly, redeveloping the Wine Australia website has to also go hand in hand with some real ecommerce initiatives mainly around tracking wine brands and enabling greater accessibility and visibility to the small regional labels and the landmark wines the paper identifies as part of the strategy.

What’s important about the Wine Australia directions paper is that it is so forward looking about the idea of strategic brand marketing. It's good news for marketers and brand agencies and that in itself is a rare drop.

Commbank takes its brand offshore.


In a move not reminiscent of the Coles Group (see DIFFUSIONblog 4 September 06: Is McCann set to give Coles a Walmart?) Australia's Commonwealth Bank has abandoned the creative work of its traditional Australian agencies and moved to US west coast agency, Goody Silverstein.

The move, reported this week in the Sydney Morning Herald, is certain to raise the hackles of incumbents STW and probably most other agencies in Australia.

More interestingly was the Herald columnists' assertion that "Australian companies (spell A_D_V_E_R_T_I_S_I_N_G) have for so long lacked any imagination or will to back interesting and engaging advertising and the ability of the communications sector to propose anything marginally outside of the predictable is remote."

Certainly that's been DIFFUSION's recent experience of adland as it seeks to perpetuate a mythic status as marginal thinkers and strategists. In fact, what we have seen is that most agencies seem content to rest on poor stale concepts and ideas and will not look for people outside the industry to change this. So, who can blame Commbank?

Just ask Optus, Singtel's Australian telecomms arm. There about to do the same thing to their Australian agencies for much the same reason. M and C Saatchi is likely to get the shove, and not without reason. Optus' "animals" were being used when I worked for Cable and Wireless in London, which dates from the time when Optus was owned by the former global carrier. So perhaps they need to be looking further afield or agencies in Australia need to work a lot harder?

The SMH doesn't let matters rest there. They put the boot in, describing senior marketing staff in Australia as "creatively retarded marketing managers". There's something in that as the dearth of great creative and well thought out brand strategy in this country is much the fault of clients as it is of agencies. Have a good look around at how they recruit senior marketing appointments. It's all through, in most cases, headhunters who work to set formulas and like their clients, rarely go outside the "predictable".

You reap what you sew.

30 April 2007

Is Australian Fashion Week and Rosemount on the same catwalk?


This year naming rights for Australian Fashion Week have gone to Rosemount Estate Wines, but is there might be a perceived misalignment between the two brands.

With Mercedes surrendering rights to Rosemount, DIFFUSION would have thought that there would have been a natural synergy between the brands as there was with its predecessor's long association.

Sure, Rosemount positions itself in the US and other markets as "The Prestige Wine of Australia" or so it's 2006 website proclaims and Australian Fashion Week, under the aegis of Simon Lock and now IMG, has successfully grown a new fashion event brand in a highly competitive but small market.

But anyone taking a trip down to their local liquor store or bottle shop will see that the "Prestige Wine of Australia" sells for less than $10 in its country of origin.

While for some this might indicate a high level of accessibility for a great wine, "prestige" and low prices seem somewhat incongruous with an international event that has helped launched the careers of such notable Australian designers as Colette Dinnigan, Akira Isogawa, Sass and Bide and Tsubi/Ksubi.

Rosemount might be repositioning, and this is understandably a long process that requires years of work, but the Fosters' owned brand also needs to translate its brand and marketing efforts to the product side, particularly in the Australian market. Sponsorships and naming rights are usually local affairs and work best when there is a perceived and actual alignment between the brand and the sponsor, not when it's merely exercising a proposition and a tagline. Even Rosemount's website makes no mention of Australian Fashion Week, an embarrassing oversight and yet another indication that the brand doesn't appear to have its brand and marketing act together in Australia.

Locally any brand that can offer itself to consumers at a range of price points below $10 (Rosemount's Diamond Range) and up to $30 for it's sparkling is not really competing with the likes of Grange or Giaconda or estates like Cape Mentelle, Domaine Chandon or Cullen.

For IMG and Australian Fashion Week, it will need to work harder to convince people that their names are synonymous, particularly as Mercedes remains a sponsor for other international events, particularly in the US. There's no details on the monetary cost of naming rights for the even but it's obviously a lucrative arrangement as the cost of showing skyrockets and major fashion names decline to appear.

Hopefully, Australian Fashion Week invitees will be supping on some of Rosemount's more pricier vintages.

14 April 2007

Prada goes mobile.


In its latest move designed to enhance its premium portfolio, South Korean electronics company LG and Italian fashion company Prada launched their a high-end luxury handset this week.

Not to be outdone by US competitor Motorola and D&G’s take on the Razr, LG's Prada mobile phone is claimed to be designed in close co-operation with the Prada design team, with both companies teaming up to distribute and market the new handset.

The phone is really a rebadged LG KE850 model but is now officially named the Prada Phone by LG. It supports EDGE connectivity and features a fully touch screen technology, enabling advanced touch interface as well as unique pre-loaded ring tones and content. Priced at around 600 euro, the Prada handset will initially be available in the UK, Germany, France and Italy, with Asian countries to follow. There is no date for either a US or Australian launch.

DIFFUSION doesn't think the Prada phone is designed to take on Vertu’s section of the market in what is a much more differentiated offer. What’s more interesting is LG's claims that Apple swiped the cool design and buttonless features, innovations included in the iPhone, set to launch in the US in June and likely to leave most of the mobile market in its wake. In our mind the Apple and Prada brands are much more aligned by attributes such as design, style and innovation than LG. The Prada phone is at a higher price point than the Apple, though it's likely they will share similar customers. And there is also no indication of what Prada is actually bundling with the new phone (store finders?). Maybe its just content with giving it a lovely Prada gloss.

04 April 2007

Google challenges TV advertising's black art.


Google's breaking into the world of television advertising sales with a new targetted model.

Launched this week in this US, Google's TV Ads enables TV advertisers to bid for spots to more than 13 million households on US satellite TV network Echostar and only pay for what is watched.

It's a major new foray into the world's more lucrative $170 billion television advertising market, after the company's recent failed attempts to launch it's Ad Sense model into print and radio.

However, at this stage the new ad sale system won't get quite as personal as its online counterpart because of US privacy restrictions.

The system will be targeted more broadly at specific demographic groups, regions and programs on one of EchoStar Dish Network's 125 satellite channels which include Discovery, CNN and MTV.

Google will be able to do a daily analysis of anonymous data collected from Dish network subscribers and only bill advertisers for that segment of an audience that actually watched a commercial for a designated amount of time.

Former NBC executive Mike Steib, who recently joined Google as head of television advertising, said that the group was already “in active discussions” with other networks.

However, Google is also likely to meet with stiff resistance from bigger US cable TV operators like Comcast, Time Warner Cable or Cox Communications, who jealously guard the data their systems generate on customer-viewing habits.

It also must face off against ad measurement competitors like Nielsen Media Research and hot start-ups like Spot Runner.

Either way, DIFFUSION believes that if Google creates the same impact it has had on the world of online advertising effectiveness its also going to have a sudden and very measurable impact on the way TV ads are sold.

More importantly, the black art of television advertising will come under even more scrutiny from advertisers, as they start to demand their agencies provide real-time measurement of active viewers and results from campaigns.

It's yet another signal for the death knell of television advertising as we know it.

26 March 2007

Coles breakup signals strategy failure.


Putting paid to his much vaunted big-box brand strategy, Coles Group Chairman Rick Allert announced today the troubled retail giant will be split and expressions of interest sought.

Despite a number 30 ranking in the global retailing stakes, Allert and CEO John Fletcher seems to have cast aside the dubious brand work of both McCann Erickson and Futurebrand and has told investors and the market that it was inviting expressions of interest for 100% ownership of the group including what they call the Everyday Needs Business (Coles Supermarkets and Kmart), Target and/or Officeworks. He also said the Group would also consider the sale of a considerable stake in the Everyday Needs Business as well as a demerger of both of Target and OfficeWorks.

Here at DIFFUSION we've been a long time critic of the group's less than comprehensible brand strategy, with Allert and Fletcher being consistently wrong footed by Woolworths. Just over three years ago Fletcher had the opportunity to set things right but even then he was saying his organisation didn't need one. It's about time other similar companies (we have a list!) woke up to the need for CEO-led wholistic brand strategy not run by their marketing departments or their advertising agencies.

Coles failure is a patent example of such strategy absence.

18 March 2007

BP tries a new shade of green.


In yet another case of corporates looking to control selected colour shades, global energy group BP has applied to the Australian High Court to secure the colour green.

Like our previous blog on Cadbury Cadbury sees red, not purple,28 April 2006 the move is the latest in the company's long running (and expensive) campaign to register the Pantone colour 348C as a trademark.

BP's new application comes in the wake of a Federal Court defeat in 2006, when the company's application to register the colour failed, overturning a previous trademark ruling that allowed the company to trademark the colour for use on its service stations and facilities. Interestingly the action was brought by Woolworths, who also use the colour greeen in their branding.

According to IP Australia, a company can own a colour if it can convince the Trade Mark Office that the colour is a distinctive aspect of its product. So while BP may call 348C BP green, having selected the shade in 1989 as the predominant colour for its service stations, the cull Federal Court in Australia wasn't convinced. It was most recently included in the revamped corporate identity.

Here at DIFFUSION most of us know that brand strategy and corporate identities in Australia built around a single colour are difficult to register. The case being that BP would have had to use the colour green alone within it's corporate identity. While BP's brand values might be founded on the idea of being green, it's corporate identity is awash with a combination of green and yellow, and thus the court saw green as only one part of the total brand identity. Further, the Court was not prepared to divide BP’s trademark into various applications to allow registration for the single colour. They ruled that the colour green by itself failed to acquire a secondary meaning and by that had not established consumer's were capable of distinguishing and recognising BP’s activities and brand from those of its competitors through the use of the colour.

Here at DIFFUSION, we wonder if in fact Pantone actually have ownership of 348C not BP. We may not be IP lawyers, but this statement from Pantone seems to contradict some of BP's claims:

...published materials of Pantone, are protected by copyright laws and include, for example, graphic presentations, color references, PANTONE Colors, PANTONE Names, numbers, formulas and software.


Pantone may not lay claim to the actual shade but they do to the registration and naming of it.

No date has been set for a hearing in the High Court.

16 March 2007

Stella McCartney gives Target some relief from cultural cringe.


Target, the Coles Group owned version of their American counterpart, have finally gotten a little design-savvy with the launch this week of internationally renowned designer Stella McCartney's winter collection.

The McCartney collection is part of a project, called "Designers for Target, style by design'' which has previously featured collections from Australian designers Melbourne's T.L. Wood and Sydney-based Alice McCall and Tina Kalivas. Unlike Target USA, this is a one-off project which illustrates some of the problems associated with the hero branding exercises like this.

Target USA are more design focussed than Australia with designers like Alessi's Michael Graves, Reidel and Isaac Mizrahi always in stock. The latest Target "Design for All" includes entire women's collections (not 14 pieces from Stella's atelier) by famed New York designers Proenza Schouler.

So why should we feel lucky we get this collection from Stella McCartney? After all she's been designing for Puma recently and the collection has been heavily featured in David Jones. And why is it only Qantas First and Business class passengers will get the benefits of design supervision by Australians Mark Newson and toiletries courtesy of Akira Isogawa and Colette Dinnigan? It all smacks a little of the old Australian cultural cringe. It's only acceptable for most people if its an overseas designer and has a premium attached to it. Here at DIFFUSION we believe good design should always be cheap and accessible. The Coles Group has had the opportunity to do this for a long time now. So let's see something from the likes of Akira, Colette and even Stella EVERY time we visit a Target Store.

Can BlueFreeway survive the Web 2?


Here at DIFFUSION we all witnessed the meteoric rise and soporific fall of digital agencies during the late 90s. Indeed, we were there in London and New York when they tried to recruit us to their agencies. The list is long and the names mostly forgettable: Scient, Viant, Deepend, Zentropy, Monday, Razorfish, Digitas, Lante, USWeb, CKS, Spray, China DotCom. Even in Australia, the likes of Attik, Spike, Deepend, MarchFirst, Razorfish all came and went with only smaller agencies and the larger integration houses surviving. So why is BlueFreeway going to be any different?

Their model is similar to those of companies like the Nasdaq-listed aQuantive, who acquired the Razorfish in 2004 and now works with leading brands to build large-scale websites and the digital marketing programs that drive traffic to them. Like BlueFreeway, aQuantive is an aggregator of digital design, marketing, performance and advertising services and has been busily acquisitive with no less than 12 companies in its portfolio spread from Avenue A/Razorfish in New York to Amnesia in Sydney. Like BlueFreeway, they range in size and market footprint.

Last week the ASX-listed BlueFreeway announced a combined profit growth of 27% across its group of companies for the six month period ending December 2006. While it was great news for those who managed to get shares in the oversubscribed float, the sustainability of the model is still under question. The results were unaudited and excludes costs associated with the Destra, which are already attacking the bottom line. Most of the agencies in the BlueFreeway group are small and perhaps with the exception of Spin and hosting company Destra, subject to the same kinds of market vagaries and pursuit of the unknown that killed so many of the more pioneering aggregation plays in the late 90s. More interestingly, like aQantive, the challenge will be see if this model can really make the kind of impact that CEO Richard Webb was able to with his former company RedSheriff. Or does Web 2 leave companies founded on old notions of how to build revenues (the traditional agency/service model) floundering?

05 March 2007

Is Starbucks on the nose?


According to a weekend report in the Washington Post, Starbucks Chairman Howard Schultz believes his stores have lost their soul. Or is he really talking about their brand essence? (see our blog 20 October 2005 The defining essence. Getting a handle on Oroton)

Quoting a leaked internal memo to his CEO and other executives, the Post reported that Schultz believes his 13,000 stores worldwide stores no longer even smell like coffee because of "flavor locked packaging".

But now the chairman of the world's leading coffee retailer seems to be onto something that should have occurred to him long ago, describing how "some people even call our stores sterile, cookie cutter." In the 14 February memo entitled "The Commoditization of the Starbucks experience", Schultz laments the the loss of "the romance and theatre" of the traditional Italian espresso machines, which have been replaced by automatic machines (in this Starbucks are not alone). Schultz wrote that the new efficient machines now commonly used in the stores block customers from watching as coffee is made and sharing what he called an "intimate experience with the barista." He obviously hasn't really visited a store recently if he thinks his staff can really be described as "baristas", when anyone who has worked their knows that a real barista does not simply press a button.

But to give Schultz his due, he is very aware of the threat from competitors who have created a more authentic coffee experience (anyone who's every bought the freshly grounf from Toby's Coffee in Sydney's Wooloomooloo would know this). Though likening them to pests who need to be "eradicated" seems to a touch colourful. More importantly, Schultz doesn't really suggest any alternatives given the scale and scope of the problme.

Here at DIFFUSION, we think it might be a good idea if the Starbucks's chairman think more carefully about how the stores could better reflect their local communities, how they might build a genuine rather than simply a differentiated brand experience and not rely solely on technologies and store layouts to maximise ROI. After all they have had to have been doing something right building the brand for the past 20 years, they must have learnt something.

A full transcript of the memo can be found at Starbucks Gossip http://starbucksgossip.typepad.com/_/2007/02/starbucks_chair_2.html
It reads:

From: Howard Schultz
Sent: Wednesday, February 14, 2007 10:39 AM Pacific Standard Time
To: Jim Donald
Cc: Anne Saunders; Dave Pace; Dorothy Kim; Gerry Lopez; Jim Alling; Ken Lombard; Martin Coles; Michael Casey; Michelle Gass; Paula Boggs; Sandra Taylor

Subject: The Commoditization of the Starbucks Experience

As you prepare for the FY 08 strategic planning process, I want to share some of my thoughts with you.

Over the past ten years, in order to achieve the growth, development, and scale necessary to go from less than 1,000 stores to 13,000 stores and beyond, we have had to make a series of decisions that, in retrospect, have lead to the watering down of the Starbucks experience, and, what some might call the commoditization of our brand.

Many of these decisions were probably right at the time, and on their own merit would not have created the dilution of the experience; but in this case, the sum is much greater and, unfortunately, much more damaging than the individual pieces. For example, when we went to automatic espresso machines, we solved a major problem in terms of speed of service and efficiency. At the same time, we overlooked the fact that we would remove much of the romance and theatre that was in play with the use of the La Marzocca machines. This specific decision became even more damaging when the height of the machines, which are now in thousands of stores, blocked the visual sight line the customer previously had to watch the drink being made, and for the intimate experience with the barista. This, coupled with the need for fresh roasted coffee in every North America city and every international market, moved us toward the decision and the need for flavor locked packaging. Again, the right decision at the right time, and once again I believe we overlooked the cause and the affect of flavor lock in our stores. We achieved fresh roasted bagged coffee, but at what cost? The loss of aroma -- perhaps the most powerful non-verbal signal we had in our stores; the loss of our people scooping fresh coffee from the bins and grinding it fresh in front of the customer, and once again stripping the store of tradition and our heritage? Then we moved to store design. Clearly we have had to streamline store design to gain efficiencies of scale and to make sure we had the ROI on sales to investment ratios that would satisfy the financial side of our business. However, one of the results has been stores that no longer have the soul of the past and reflect a chain of stores vs. the warm feeling of a neighborhood store. Some people even call our stores sterile, cookie cutter, no longer reflecting the passion our partners feel about our coffee. In fact, I am not sure people today even know we are roasting coffee. You certainly can't get the message from being in our stores. The merchandise, more art than science, is far removed from being the merchant that I believe we can be and certainly at a minimum should support the foundation of our coffee heritage. Some stores don't have coffee grinders, French presses from Bodum, or even coffee filters.

Now that I have provided you with a list of some of the underlying issues that I believe we need to solve, let me say at the outset that we have all been part of these decisions. I take full responsibility myself, but we desperately need to look into the mirror and realize it's time to get back to the core and make the changes necessary to evoke the heritage, the tradition, and the passion that we all have for the true Starbucks experience. While the current state of affairs for the most part is self induced, that has lead to competitors of all kinds, small and large coffee companies, fast food operators, and mom and pops, to position themselves in a way that creates awareness, trial and loyalty of people who previously have been Starbucks customers. This must be eradicated.

I have said for 20 years that our success is not an entitlement and now it's proving to be a reality. Let's be smarter about how we are spending our time, money and resources. Let's get back to the core. Push for innovation and do the things necessary to once again differentiate Starbucks from all others. We source and buy the highest quality coffee. We have built the most trusted brand in coffee in the world, and we have an enormous responsibility to both the people who have come before us and the 150,000 partners and their families who are relying on our stewardship.

Finally, I would like to acknowledge all that you do for Starbucks. Without your passion and commitment, we would not be where we are today.

Onward…


.

25 February 2007

Coles brand backflips.


As DIFFUSION predicted (Is McCann set to give Coles a Walmart 9/4/06) Coles Group's roll out of it's new brand strategy is proving problematic.

Firstly, the much heralded closure of the Bi-Lo brand has not resulted in customers flocking to Coles supermarkets, as was hoped, but to competitors like Woolworths, Aldi and those pesky IGA stores. What this is likely to mean is that its other brands (K-Mart, Vintage Cellars) in the portfolio also slated for the chop are likely to be left standing while John Fletcher and those masterminds at McCann Erickson and Futurebrand rethink the much vaunted supercentre approach. Yes, supercentre is what they are going to be called. Just check out a recent National Retail Manager role Cole Group advertised two weeks ago describing the Coles Supacentre as "radically transforming the retail experience in Australia".

Secondly, there's the tiny issue of an imminent-any-time-any-day-now-soon sale after Fletcher and Coles Group Board chairman Rick Allert decided to throw in the towel and succomb to the inevitable private equity tsunami engulfing some large underperforming listed companies throughout Australia.

Thirdly, Coles Group's current lacklustre trading performance is putting even more pressure on Fletcher and Co to get the new strategy right. Here at DIFFUSION we've received word from Tooronga that there's quite a lot of internal dissatisfaction with the new direction. Insiders are wondering whether the new strategy is going to work.

In the end, it might all be for nought. If, after an equity group breaks it up and Woolworths nabs Coles' best performers Target and OfficeWorks, what will they be left? An underperforming supermarket chain and a lacklustre variety store. Hardly the stuff of dreams.

09 November 2006

The politics of attack advertising.


According to the definition by the US Centre for Media and Democracy in it’s SourceWatch www.sourcewatch.org/, an attack advertisement is a short, 15-60 second piece of political advertising usually on the electronic media and almost always aired during an electoral campaign, but maybe as a third party ad. It is a key feature of negative advertising and is often used to discredit a political figure or message. An attack ad is negative advertising but it also consitutes a new form of advertising, using some of the elements found in propaganda.

The most recent examples are those which have been used by both parties and independents during the recent mid-term elections in the United States and in Australia by the Labour Party, as part of an advertising campaign criticising Prime Minister John Howard’s trustworthiness and honesty over interest rates. There is also some talk attack advertising will be a feature of some of next year's State elections in Australia by the Labour Party.

The current campaign features billboards and commercials which portray John Howard as Pinocchio (see picture), whose nose has grown longer with each of the past seven interest rate rises. The campaign mocks his 2004 election pledge "to keep interest rates at record lows" and asks: "Who do you trust now?"

Common features of such an attack ad include conceptual metaphors that can serve to smear opponents (hence John Howard as Pinocchio), memorable sound bites intended to be repeated by the public on the street and in discussions about how to vote and to avoid libel claims, using deliberate ambiguity, fatuous and extreme assertions, which go beyond legal liability

All of this can also be delivered with a degree of humour.

So if the attack ad fails, an attack ad campaign can be "spun" into "good fun" by simply extending the conceptual metaphors or extreme assertions to humorous lengths.

Attack ads utilise a variety of familiar propaganda techniques to influence opinions. Attack ads may be presented through a variety of broadcast or print sources but usually are intended to deliver a specific message to a select audience. Rather than support a position held by the advertiser, attack messages target an opponent's platform, track record, background or character.

But for an attack ad to be really effective, the message probably needs to be believable. Repulsive imagery conveyed in attack ads might reinforce allegations or mask outright character attacks. The ads often rely on the resonance of the message to attract the attention of target audience members to a message most other listeners or viewers will ignore.

Let’s judge later the effectiveness of current attack advertising after the US mid-terms and maybe even see if Australian Prime Minister John Howard starts to develop a credibility gap. But according to Wikipedia http://en.wikipedia.org/wiki/Attack_ad some believe that attack ads are useful in shaping public opinion with some analysts claiming the effects can be as great as five percent change. However, it’s a fine line if an attack ad may fail in its intended purpose and backfire against the group which first used it. For example, if an ad is seen as going too far or being too personal the voters will turn against the party that put out the ad. There will be examples of this to be found in the mid-terms.

In the US, research has consistently found that negative advertising has positive effects. Finkel and Greer (1998) said negative advertising “is likely to stimulate voters by increasing the degree to which they care about the election’s outcome or by increasing ties to their party’s nominee.” This is an important feature of negative campaign advertising because it can solidify a candidate's support going into an election. The finding was repeated by Goldstein and Freedman (2002), who found that negative campaign ads raise interest in the election as well as raise the perceived importance of the election, which increases voter turnout (an important factor in non-compulsory US voting).

Here at DIFFUSION we don’t expect attack advertising to remain the sole property of political parties and their advertising agencies or even of political campaigners. What we see is the wider application of attack advertising into more general fields, designed to attack competitors or to dispute product or service claims. Either way, the ground has been established for their use and their effectiveness to mobilise a purchase decision has been proven.

04 September 2006

Heinz HP sauce goes dutch.


One of Britain’s most iconic sauce brands is likely to become another victim of a point of origin fraud with company owners Heinz announcing the brand is going to be made by the Dutch.

HP brown sauce (yes, we even have it in Australia) famously features the Houses of Parliament on its label and the announcement last month that it US parent Heinz wants to close its plant in Birmingham and move production to Holland has sent shockwaves through Britain. The sauce has been made in Birmingham for 103 years and the move will likely result in the loss of both jobs and the brand's most favoured status as the UK parliament’s brown sauce of choice.

Even more interesting is the proposal by rivals Branston to consider adopting the same symbol on their own Branston brown sauce bottle. Heinz' move has sparked off another round of hand wringing by the British about the importance of “Britishness” and point of origin as an emotional and pivotal part of culture.

Here at DIFFUSION we’re both defenders of point of origin and truth in labelling as important elements of brand heritage (see blog 7 February 2006 Points of Origin)

Is McCann set to give Coles a Walmart?


Why is that when a company has a weak or non-existent brand strategy they try and fix it with advertising?

Coles seems to be desperately trying to bolster what is widely regarded by the market as a flimsy brand strategy, by drafting the help of senior New York McCann Erickson advertising executives, according to the Sydney Morning Herald last week.

McCanns' is working alongside their Interpublic Group stablemates, FutureBrand, on a reported combined monthly fee of $750,000 and the team includes some Walmart account veterans - so we think we know where this is going. Coles had previously only made a few quiet asides about FutureBrand's involvement in the rebranding, unveiled at its much maligned strategy presentation at the end of August.

DIFFUSION thinks maybe the reticence by Coles Group chief executive, John Fletcher, to provide more details on the strategy was because it hadn’t really been worked out. Now that McCanns' have weighed in, it’s likely any strategy will be one led by massive brand advertising rather than the much needed fundamental brand analysis.

Yet there’s going to be a lot more work to be done on the proposed “everyday needs" monolith before Coles puts it in front of shareholders at the next presentation in November. The Coles Express, First Choice, Liquorland, Vintage Cellars, Kmart and Theo's Liquor names are all set to be axed for the single disingenuously named brand.

We’re still scratching our heads about the decision to axe both Express and Vintage Cellar brands. Express has been the bulwark for Coles' hugely successful foray into forecourt marketing and with the sale of Myer, Vintage was the only premium brand left in the portfolio with neither Target or OfficeWorks filling that space. It’s all down market from here; which leads us to ponder...

While Walmart's business model, as the 'king' of low prices, makes it the envy of retailers around the world model, DIFFUSION hopes Coles will not be following in its path. Consistently ranked in the top 10 of most crisis prone organisations in the US, Walmart's human resource, social and environmental policies have left its public in uproar.

In addition, we believe that international trends (aside from the US who still seem to be locked into the bigger-brighter-better-is-best notion) are indicating a move away from monolithic brands towards portfolio brands, with which customers can build more intimate relationships; it's also a smarter risk management strategy - if one brand fails, it will not affect the rest of the portfolio.

The advice we hope McCann is giving Coles is culturally sensitive to how, and from whom, we want to purchase in Australia. They should acknowledge the mistakes monoliths such as Walmart have made and base the new strategy on international best practice that is simply not US-centric.

18 August 2006

Polo Ralph Lauren goes immersive.


We've been talking about it for some, well ever since THAT Tom Cruise movie...yes the 2002 blockbuster Minority Report...and it seems like we were not the only ones who thought that immersive marketing was not too far away. First Eyecorp (see blog 18 March 2005, 'Minority Vision') and now Ralph Lauren.

Polo Ralph Lauren have just launched a new interactive window in their Madison Avenue shop that allows shoppers to choose and purchase an outfit projected on the shop window, even when the store is shut.

“After watching Steven Spielberg’s Minority Report, I really wanted to find a way of making that amazing technology a retail reality. We are thrilled to offer such a unique and exciting way for our customers to further explore the world of Ralph Lauren; with this initiative we are reinventing the concept of shopping anytime” said David Lauren, Senior Vice President Advertising, Marketing and Corporate Communications of Polo Ralph Lauren.

It's a classic case of life imitating art.

04 August 2006

Coles tries on a new lite strategy.


On Monday 1 August the Australian supermarket giant Coles went public with the results of their eagerly awaited nine month internal review. They were greeted by a lukewarm market reception and bewilderment as to the scope and nature of their new brand strategy.

Coles CEO, John Fletcher, said the newly named 'Coles Group Limited' (as we predicted in our blog on 13 July 2006) complete with a bright curly cue logo would "drive sales and earnings growth by further simplifying its business to invest in stores and customers’ shopping experience" by focussing on "customers’ everyday shopping needs".

The most interesting part of the announcement was the decision to integrate the existing food, liquor, fuel and general merchandise businesses (Coles Supermarkets, Liquorland, Vintage Cellars, 1stChoice Liquor Superstore, Coles Express and KMart) into something vaguely called "everyday needs".

While the Sydney Morning Herald's coverage on the same day seemed to interpret this to mean that everything would be called "Coles", our understanding is that while the Coles name would feature prominently in the newly branded business, this is not necessarily the case...

In addition, we are not convinced that calling something "Coles Everyday Needs" is particularly evocative of anything. Perhaps really what they are trying to do is simplify the group structure so that the process of marketing, supply chain and management can be centralised and significant savings made by reducing head office numbers and duplication at various management levels of the existing brands.

Fletcher claims that the Group will be spending $60 million to improve the customer experience in supermarkets and increasing investment in Target and Officeworks, which they have chosen to retain. Yet, why announce such a large spend working on what is demonstrably a poor experience (which you will be inevitably looking to rebrand over the next two years)?

“We have spent the last nine months researching our customers, team members, suppliers and the world’s best retailers to ensure there is overlap between our current and next strategic direction,” Fletcher said in the company release.

This is a very strange claim when both DIFFUSION and most market analysts remarked that the Group lacked any real strategic direction.

“During this time it has become clear that two key themes – customer intimacy and simplification – will drive future growth, enabling us to direct additional resources and focus to engaging our customers with better service, more convenience, and better products and rewards.”

Similarly, Fletcher's claims that these two themes are the bulwark of any future growth are also odds with a culture that to date has seemed to shun any notion of better service by reducing the ratio of staff to customer numbers, defined 'convenience' by opening hours, marginalised suppliers by screwing ever better deals and increasing its reliance on own brand products (see our blog on 18 March 2005) and vastly diminished rewards for customers by increasing eligibility thresholds.

Fletcher is now working on the idea that the "key to the new everyday needs business will be the creation of a lean and innovative culture in which stores are ‘heroes’, and where team members are empowered to deliver great service and products to customers.”

Fletcher's description of the new stores in terms of both "innovative" and "heroes" seem a contradiction in terms. Under his stewardship, the Group's brands have been denuded of any real intrinsic value and supported by bland propositions. The "everyday needs" proposition is equally fraught. Will the new store formats that Coles will invest something like $850 million in, become hypermarkets, along the lines of Carrefour or WalMart?

We don't know the answer because Coles and Fletcher is still working out the details of what can only be described as a strategy that not only views brand as the sum of a capital spend but also takes for granted the notion that customers are more interested in logos and fascias, rather than details of how they might actually get better service.

31 July 2006

DIFFUSION talks brand at PRIA.

Discussion points from the 'Senior Practitioners' Cocktail Roundtable Event', 1 August 2006, Public Relations Institute of Australia.

DIFFUSION director Stephen Byrne discussed the importance of developing a brand strategy as a primary business requirement against the context of effective public relations and communication planning.

Brand strategy within business and communication planning

The idea of integrated communication, which holds that all communication emanates from a single strategic platform, has largely failed. A number of underlying currents have been largely responsible for this:

1. Agencies are constrained by their media bias
2. Business structures don't mirror integrated communication planning
3. Development is too far down the value chain to be effective, and
4. Brand strategy is silo-ised by being viewed as a marketing and communication activity

Most companies are focussed on action and tactics, rather than an actual brand or communication strategy. The need to demonstrate branding success through empirical evidence, often replaces planning. So a brand strategy, if it exists at all, becomes synonymous with a set of tactical communications developed by tactical specialists often working in isolation.

A holistic business strategy, with brand as an essential part of it, provides strategic intent which can help unite and integrate all communication activities - such as public relations, advertising, investor relations, interactive or internal communication.

Any brand strategy must begin with understanding the role of brand within the business model and determining how best brand can help grow and sustain the business. Brand strategies should engage the highest level of management because it brings strategy, finance, marketing and communication together, to manage the brand.

Towards a business brand strategy

Ten steps necessary to build a successful a brand–based communication program:

1. Understand, formally define and acknowledge brand in your business planning; have a formal brand strategy
2. Understand those factors that contribute to the creation of brand value
3. Identify and understand all your audiences
4. Define your point of difference and build value propositions around that
5. Work out how you can clearly enunciate your point of difference so that audiences understand it
6. Create messages
7. Identify and define the role of each medium in changing perceptions and sustaining communication momentum
8. Determine an appropriate communication mix
9. Only develop those communication activities that support brand
10. Review and revisit from 5.

Brand’s role in holistic business planning is an organic process. Always return to your strategy to check whether all the assumptions you have made are still valid and correct.

http://www.pria.com.au//events/id/227

20 July 2006

Is Coles still Myer for Xmas?


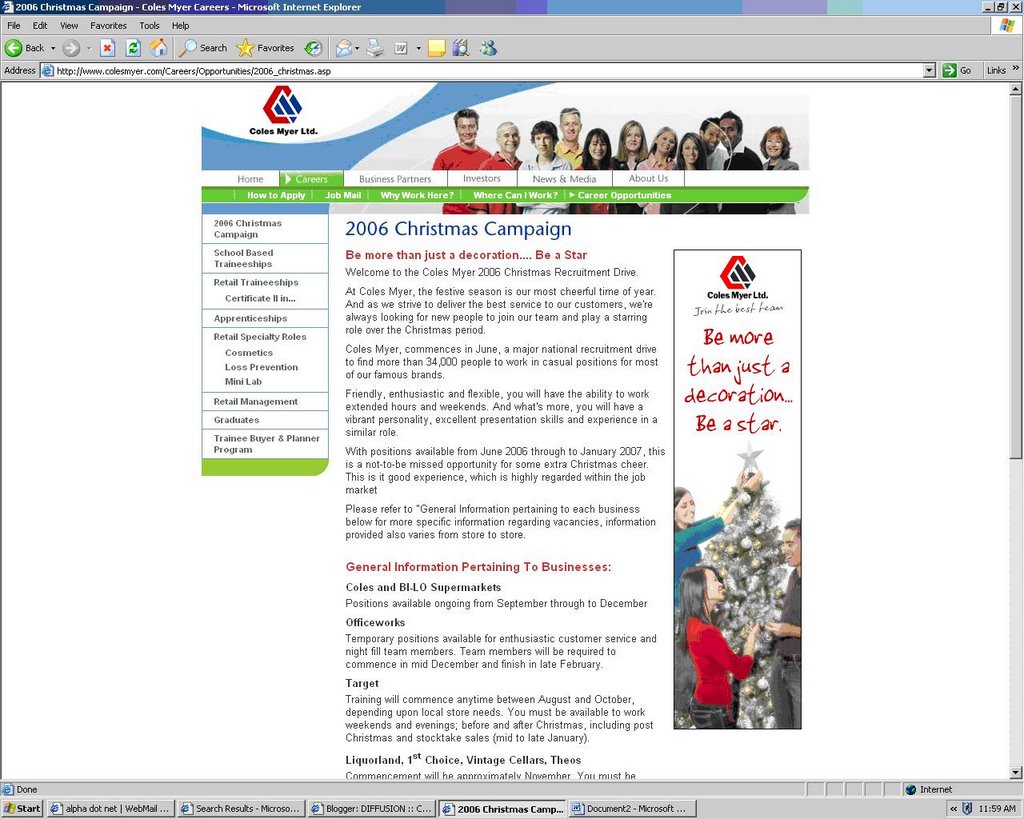
Picking up a bottle of wine in our local Vintage Cellars this week, DIFFUSION was interested to notice a flyer for casual positions available at Coles Myer brand stores during Christmas 2006. While we are not sure about the copy, “Be more than just a decoration…Be a star” (what exactly does this mean?) we were more interested to note the inclusion of the MYER logo on the flyer. Now we know that festive season recruitment starts early but with the confirmed sale of MYER happening in March, we'd like to think that by mid-July they might have had an opportunity to think about a reprint? That said it's nice to see Coles Myer with a new cleaner, brighter and more functional website (with not a MYER logo in sight)!

Cadbury appeal: short a full glass and a half.


It seems Cadbury's love of the colour purple knows no bounds [see DIFFUSION blog 28 April 2006, ‘Cadbury see red, not purple’]. According to the Sydney Morning Herald the company is lodging an appeal “against a Federal Court ruling that it does not own the colour purple”. The justification used by Cadbury according to its Corporate Affairs Manager, is the significant investment “in marketing our products using Cadbury purple in Australia”. Once again, the target of their ire is Darrell Lea, who no consumer would accidently put in the same shopping basket as Cadbury. At DIFFUSION we believe that Cadbury would see a better return on their now considerable legal fees if they focussed on developing marketing activities that encouraged ownership of the colour purple in the consumer's (rather than the Court's) mind. This was, in part, one of the comments made by the judge in the original suit. Surely this would resonate more with customers and is, after all, what really counts. But then perhaps if that fails they could return to their original shade of 'lavender'.

13 July 2006

Tsubi begets Ksubi.

Following our 18/4/06 post 'A Fashion in Names: Tsubo vs Tsubi', the wacky boys at Tsubi have reached an out of court settlement with US shoe label Tsubo following a trademark infringement dispute.

Tsubo argued in a New York court that Tsubi's use of the first four letters of its name was a breach of its trademark, which was established in 1998 and had been registered in Australia in March 2000, two years before Tsubi.

The dispute settlement terms means Tsubi will keep its name in Australia but will now be known as Ksubi in the rest of the world.

It's an interesting result as DIFFUSION shared the view that Tsubo's case was, in part, mischievous, as both operated in very different parts of the fashion world. However, now Tsubi faces the daunting task of rebranding for the rest of the world and creating a new identity and name recognition for the new brand name, Ksubi. Let's hope they did their homework this time on the new name.

10 July 2006

Opening up communication with doctors.


We were pleased to hear about the “new wave of students upon whom educators have pinned their hopes for a generation of communicative, motivated and engaged doctors” (Sydney Morning Herald, 5/7/2006). After our critique (see blog ‘Doctoring language’ 16/9/2005) of doctors who practice what we referred to as ‘ethnocentric’ communication; a view of the world where members of their own group [other medical and related health care practitioners] are valued and understood, while nonnatives/others [patients] are as seen as “fundamentally different and therefore deserving of different treatment” (Grimes & Richard 2003).

While University of NSW Professor Rakesh Kumar points out that the new entrance interview procedures have produced “students who are much more willing to get engaged in the learning process” and according to Newcastle University research, students who are “more likely to perform well”, DIFFUSION would like to know if communication (as a professional practice) is an integral part of the course?

It is commendable that, as Professor Tiller states, the interview procedures gauge if “they (the students) have an ethical background… they (can) decide what's honest and dishonest", here at DIFFUSION we know that being an effective communicator is much more complex than this.

And we're sure that if you asked the majority of doctors if they practiced their profession without prejudice, they would say resoundingly ‘yes’. Yet, as we have pointed out, ethnocentric communication is much more complex than this…it acts to keep others [patients] behaviour predictable (and safe) through the use of simplified scripts. As a result, we often feel ‘spoken down to’ or ‘discriminated against’ when visiting our local GP. Often without realising, doctors make a pre-judgement about their patients, based on the learned doctor/patient societal roles. It is these roles and related communication that needs to be challenged.

Here’s hoping that the new breed of doctors take their communication as seriously as their Hippocratic Oath.

13 June 2006

The irony of Coles' Liquorland.


Does the Coles Group (we’ll call them that because in the wake of the finalisation of the Myer sale they haven’t gotten around renaming themselves yet) understand irony? It seems not if we are to understand this sign prominently displayed out the front of one of their newly renovated Liquorland stores. While EBIT and sales are up by 5%, the chain has been in constant state of brand repositioning since 1996, when the new logo was launched. Now Liquorland is going further down-market with prices to match.
While this hints to some degree of strategy within the Group and might seem a good thing to some people (Coles), it’s not so for those suburban markets where Coles and rival Woolworths control many of the liquor outlets and deem that a single suburban area cannot support BOTH their premium liquor store offerings, Dan Murphy and Vintage Cellars.

All the more reason for the ACCC to keep a close watch on the territorial carve ups that have resulted from their aggressive entry into the lucrative Australian wine and liquor trade industry.

06 June 2006

Will Coles and Woolworths pump for TV?


Brandweek reports US companies, Murphy Oil and Gas Station TV have announced the signing of a joint agreement for broadcast television at petrol pumps. The deal includes ABC programming including local news, sports, weather and traffic with some original content and advertising. In the wake of a planned rollout of instore TV channels by both Coles and Woolworths and their successful petrol company partnerships, DIFFUSION sees this as an obvious new opportunity for the dynamic duo-poly. Harold Mitchell will be happy.

26 May 2006

Labor needs a mirror in AWB rebranding call.


Australia’s Labor Opposition has jumped on the renaming and rebranding bandwagon.This time it's over the controversy surrounding the Iraq kickbacks scandal and the Cole inquiry.

According to Federal opposition foreign affairs spokesman Kevin Rudd, the future of Australia's wheat farmers must be considered in any name change and makeover of embattled wheat exporter, the Australian Wheat Board (AWB).

Rudd said the reputation of Australia's wheat farmers must not be affected during AWB's change process.

Strangely enough Rudd seems to have got it wrong when he issued the announcement before the release of the AWB’s half-year profit result.

According Labor, AWB was expected to unveil a management clean-out, several board resignations and a name change to distance the company from the controversy. Nothing has happened, well at least not yet.

And while AWB’s half year results were poor, it dismissed the effects of the Cole enquiry on its brand, describing it as "solid" and said that wheat exports were only one part of its business and it was repositioning itself as a provider of financial services to the rural sector.

DIFFUSION thinks that the AWB would do well to examine the impact of the Cole Enquiry on both its domestic and international brand through brand equity analysis and measurement. Successive blunders from senior management seem to point to a real failure to develop more robust internal and external crisis communication planning and tracking.

More so, Rudd’s comments seem rather disingenuous considering Labor, suffering from a prolonged crisis of identity compounded by successive electoral failures, has itself failed to effectively rebrand and reposition.

28 April 2006

What is diffusion?


It seems that a lot of our blog traffic here at DIFFUSION is actually trying to find out what the term 'diffusion' is all about. When we started and named the company in 2002, we were interested in how ideas and consequently brands were created and spread, hence the name, DIFFUSION.

But here’s a ready reckoner of terms. We’d be interested in hearing about others.

1. According to the Oxford English Dictionary there are five meanings for this noun (incidentally, the word has not changed from its Latin generation). The first three all relate to the idea of “outpouring”, “spreading abroad” and “dissemination”. The fourth meaning refers to prolixity (something we at times are unfortunately prone to) and the fifth is a scientific term which formed part of our initial inspiration. This is the idea that light when reflected is scattered via diffusion and atoms, molecules and ions are randomly moved from one site to another through the process of diffusion.

2. The French word “bricolage” is closely related to how we envision the idea of diffusion. The random assembly, construction or creation of things and ideas, also occurs through an act of diffusion. This term is now being used by a diverse range of professions from filmmakers to researchers in the humanities.

2. In marketing terms, we bow to those knowing folks at the wikipedia (http://en.wikipedia.org/wiki/Early_adopter), diffusion is the process by which a new idea or new product is accepted by the market. The rate of diffusion is the speed at which the new idea spreads from one consumer to the next. Adoption is similar to diffusion except that it deals with the psychological processes an individual goes through, rather than an aggregate market process.

3. The American Marketing Association defines it in advertising terms (why are we not surprised?) They describe it as a model representing the contagion or spread of something through a population (we hoped we were contagious). Diffusion models in marketing are often applied to the adoption of a new product, or the exposure of potential customers to some information about a product (hence, the advertising message).

4. Diffusion in fashion seems to work the same way as marketing models…originally fashion design, as we know it, was centered on Paris and the salons of designers like Chanel, where clothes were created for local clients, but the styles were diffused to many other countries. This highly centralized system changed with the onset of mass production and then mass media and has now been replaced by a system in which fashion designers in several countries create designs for small publics in global markets, but their organizations make their profits from luxury products other than clothing eg. LVMH, Gucci, Armani, Hermes. Trends can now be determined by fashion forecasters, fashion editors, department store buyers and even bloggers. Manufacturers and retailers are increasingly consumer driven and market trends originate in many types of social groups, including subcultures. Consequently, fashion now emanates from many sources and diffuses in various ways.

Cadbury sees red, not purple.


A colour can function as an important part of a company's brand identity and in some cases can even be seen as intellectual property. A colour adds to brand value in a variety of ways, including aiding brand recognition, differentiation and evoking consumer emotion (e.g. the name and colour "Orange" for the British mobile company and the colour and word "brown" for the global courier company UPS). Colour can also become a rallying point for a company seeking to create a seamless brand experience and be used to stimulate consumer behaviour as in Apple's adoption of white for the original Ipod (see our blog on 16/8/05 Silver is so turn of the century.).

So can a company or organisation own a colour? It seems so but not always.
In 1987 Owens Corning made legal history as the first company to trademark a color, in this case, pink, and as far as fiberglass insulation goes it seemed to set a benchmark for the corporate ownership of colour. The difference was that Owen Corning was granted the trademark because limiting others from using pink as a fibreglass colour wouldn’t create a barrier to entry to others, but it seems that some companies aren’t able to ostensibly see this point of view.

Which brings us to Cadbury; "All brands and logos/images accompanied by ® or TM, and the colour purple are Cadbury Group trade marks in Australia. © Cadbury Schweppes Pty Ltd 2004." However, this week Australia's Federal Court has told Cadbury’s, again, that it does not "own" the colour purple in Australia, as its latest attempt to secure use of purple by suing rival Darrel Lea in a protracted trademark dispute failed.

This is the second time Cadbury has attempted to trademark the colour. Cadbury’s original trademark application was made in November 1998 and was described as follows:

“The trade mark consists of the colour PURPLE the said trade mark being adopted as the substantial colour of packaging used in relation to the nominated goods.

The colour is the shades of purple corresponding to the following references in the 1997-1998 PANTONE Colour Formula Guide: 2597c, 2607c, 2617c, 2627c, 266c, 267c, 268c, 269c, 2685c, 2695c, 273c, 274c, Violet C, 2735c, 2745c and 2755c”

At the time the application was only for chocolate and chocolate confectionery.

In 2002 the Australian Trademarks Registrar rejected the company’s attempt on the basis that the evidence presented in the hearings “simply does not show that the purple packaging was functioning as a trade mark at the relevant date, nor that it distinguished Cadbury's chocolates from those of other traders,” said Senior Examiner Deirdre O'Brien. She added that she was not satisfied that, at the date of filing, “if consumers had seen a chocolate block in a purple wrapper, they would have known that colour as a Cadbury trade mark.” Seems nothing much has changed and as far DIFFUSION is aware, the trademark is still pending and hence the decision by the Federal Court.

But Cadbury already claim the dark shade of purple as a global trademark after successful registration in both the UK and New Zealand and launched its action in 2003 to sue Darrell Lea for "passing off" (hard to see how it could do this when it has no trademark in Australia).

Cadbury had objected to Darrell Lea's use of various shades of purple in the rival store’s signage, uniforms and product packaging and claimed that in its original trademark application it applied to have included the colour for use in 17 categories including soaps and perfumes, jewellery, kitchen utensils, clothing and leathergoods (not what you'd expect a chocolate company to claim!). DIFFUSION guesses they were thinking of some very wide brand extensions here.

But Federal Court judge Peter Heerey found that Cadbury, as in the 2002 trademark ruling, had no exclusive claim to the colour and ruled the case against Darrell Lea or any one else Cadbury had threatened, could not proceed. He said he was "not convinced" Darrell Lea had attempted to pass off its goods as Cadbury products or that it would attempt to do so in the future.

Which brings us back to ownership of colour. In the case of Cadbury, while it may not be possible for the company to trademark the colour purple in Australia, perhaps they should have been looking for other ways to enforce the use of colour? Marketplace recognition doesn’t take place overnight and it's probably missed the boat on purple.

Now it seems companies have yet another reminder that attempting colour ownership can make you see red.

18 April 2006

A fashion in names: Tsubi vs Tsubo.


Fashion naming and branding is sometimes a complex affair or is made out to be. Often companies in different markets compete for the same or similar names without anyone batting an eyelid. In Sydney everyone knows that there is a Hermes Leathergoods who make handbags in St Peters, yet they are allowed to exist by the Hermes conglomerate, who own the more luxurious moniker among other names. So when two marginal funky brands - Tsubo, out of Los Angeles and specialising in shoes and Tsubi, out of Sydney and originally a jeans maker venturing into clothing and accessories - start arguing, you wonder if this a beatup by Tsubo or the Sydney Morning Herald http://www.smh.com.au/articles/2006/04/17/1145126056425.html, who report it.

In what seems a parochial story, the Herald’s article claims that Tsubo's founders think the Tsubi name is “too similar to their own brand name, established in 1998 and registered in Australia in March 2000”. So what we ask? Registering a name in a foreign market does not give necessary exclusivity, nor does it mean passing off as the name goes through domestic business name and trademark checks for any similarity. According to the Australian Securities and Investments Commission (ASIC) Tsubi registered its company name in November 2000 and its first trademark in 2002. Tsubo, on the evidence of our ASIC search, is not even registered in Australia as a business name or a company.

However, it seems that the matter is likely to play out in U.S. courts where, the Herald reports, that “after years of informal requests for Tsubi to change the name, Tsubo had started legal proceedings” against Tsubi in the Federal Court in New York. And surely this is perhaps where the money is and the real issue lies.

Also at dispute is the similarity between the two logos, with Tsubo claiming both brandmark fonts and logo design are similar. Interestingly, Tsubi’s logo is only registered in Australia for use on it’s newly launched sunglass range. Again, DIFFUSION wonders whether there is anything to dispute here. We know Tsubi only registered a mark for it’s eyewear label but otherwise the mark has been somewhat fluid (we couldn’t even find a definitive version on tsubi.com), so only have these two to compare.

The important thing is that both brands operate in distinct sections of the fashion market and while both are marketed and sold in Australia and U.S., any name confusion is going to have to prove some level of economic damage. It’s going to be difficult for Tsubo to prove that either its name or logo are being either traded-on deliberately by Tsubi or that Tsubi has deliberately copied aspects of the Tsubo logo as Tsubi’s mark, has been up to this time fluid and is not, as far as we are aware, registered for use in the U.S.

However, Tsubi, which probably has more of an international brand name to protect, would do well to look at both name registation and trademark registration in all markets it operates in and intends to market in, otherwise this action is likely to continue. Perhaps Tsubi’s owners are either being naïve or deliberately so?

22 March 2006

Newbridge look for value in Myer minus Coles.


New Myer owner, Newbridge Capital must have recognised something in the ailing Myer chain that others didn’t.

With an extremely modest $A60M estimated EBIT for this financial year, the $1.4B Myer sale price seems pretty high. However, Newbridge [www.newbridgecapital.com] believe in “unlocking value; recognising that value is often hidden in companies”. An item of great value that has been overlooked by Coles Myer Limited is the Myer brand. But "overlook" is perhaps not quite the right word as it implies neglect and Coles Myer can be accused of so much more than negligence.

Single-handedly Coles Myer has re-positioned the Myer brand to a place that has no resonance with its customers or communities, no differentiation from its competitors and no personality [see blog 8/2/06 ‘What’s the real value of the Myer in Coles Myer?’]. In addition, its heritage both as an intrinsic part of the Australian retail landscape, the community significance of the Myer family itself [thankfully now part owner] and in NSW, the richness of the Grace Bros. brand has been ignored [see blog 14/10/2005 ‘No one will save Myer now’].

Myer’s brand is valuable and with some TLC can be resuscitated. New Myer boss Wavish’s starting point of hearing “...what both the staff and customers have to say about the brand before we finalise any of our plans” [Sydney Morning Herald 13/3/2006], is vital. But what DIFFUSION would like to know is how this information is going to be collected, managed and translated into a real, meaningful and living brand?

Newbridge and Wavish need to treat the Myer brand as if it has been through a crisis [which in some ways it has], developing a brand recovery strategy that takes into account the past, the present and the future. The looking back and then forward process should uncover meaning and value that will stand the company in good stead for the long term – an imperative of Newbridge who “focus on investing in companies that have a sustainable long-term advantage over their competitors”. From this, a brand strategy should then be developed as an integral part of the business planning process, to place Myer on target to achieve their real potential of $240M EBIT [The Age 17/3/2006].

As we note in our previous NAB blog, the process of brand valuation is not achieved by a mere whip around to see what everyone thinks but is complex, overarching the whole of business and needs to be properly managed if it is to provide a real and lasting return.

NAB's new brand of wishful thinking.


Last month Australia's largest lender, the National Australia Bank (NAB), unveiled its revamped corporate logo and a new take on what is a decidedly uninteresting but functional name, 'nab'. Like most rebrands, NAB’s is no different - a redesign can cost millions, most of which is spent on standard roll out of a new mark. Buildings, websites and a whole lot of collateral, are reshaped and shredded to suit the new look (don’t get us started on the fact that even their new brochures still apply the superior case!). Cheques, letterheads, pens and business cards are binned and replaced. However, what is disappointing about this latest corporate makeover is how much it seems more of an attempt at papering-over the cracks in the organisation, than a radical re-envisioning.

One of the reasons cited for the rebrand was the NAB’s 2004 foreign exchange desk scandal, which saw it lose $360 million and consequently it’s CEO and much of its senior management team.

Interestingly some sections of the market have taken a completely different view of the makeover. Analysts seem to have a view that these kinds of spackfilla jobs “win no leverage”.

"The brand name and image is something that is more important to its customers - particularly retail customers. It's not a fact that is likely to drive a price-earnings model", said a Citigroup analyst quoted in the Sydney Morning Herald.

DIFFUSION finds comments like this somewhat disingenuous. Most company valuations always take an account of brand equity and in the case of NAB, there was a significant loss of equity when the FOREX scandal hit.

Traditionally brand valuation consists of four main strands covering fundamental financial and balance sheet analysis, contextual market and consumer analysis, brand analysis examining brand as a determining factor in the future earnings and the value accorded the brand and mark as intellectual property. A number of factors can be added under these headings and weighted according to their importance or relevancy. Consumer analysis, for example, should include customer satisfaction, brand preference, quality perceptions, value for money and good service while market analysis should include share of market, share of voice and growth statistics. Any financial analysis would include profitability, sales and margins forecasts. All of these can be combined to give total brand value and as such a price-earnings model does take account of the impact of customer sentiment on overall earnings.

Secondly, while NAB CEO Ahmed Fahour acknowledged during the week of the relaunch, "I've got the number one business bank in this country I've got the wealth management business. I've got a smaller but turning-around retail business. And the fact is that I can have one consistent conversation with you and we are all singing from one hymn sheet," there is also the need for organisations such as NAB to use their brand to be one of the determinants of their dialogue and interaction with customers. It’s not good enough to just trot out what is rather poorly realised signifier alongside the diminutive name; in NAB’s cade, the follow up to their rebrand, the new brand promise needs to be sold through the organisation.

When DIFFUSION talked to one of the nice NAB counter staff after the re-brand, they acknowledged that they had no real involvement in the process and didn’t know what what the new brand promise “We believe in people with ideas and dreams. Helping you fulfil yours is at the heart of everything we do” really meant.

So will customers see a different organisation and feel any different? Can a bank, or for that matter any institution or organisation, really help you to realise your “dreams”?