18 April 2006

A fashion in names: Tsubi vs Tsubo.


Fashion naming and branding is sometimes a complex affair or is made out to be. Often companies in different markets compete for the same or similar names without anyone batting an eyelid. In Sydney everyone knows that there is a Hermes Leathergoods who make handbags in St Peters, yet they are allowed to exist by the Hermes conglomerate, who own the more luxurious moniker among other names. So when two marginal funky brands - Tsubo, out of Los Angeles and specialising in shoes and Tsubi, out of Sydney and originally a jeans maker venturing into clothing and accessories - start arguing, you wonder if this a beatup by Tsubo or the Sydney Morning Herald http://www.smh.com.au/articles/2006/04/17/1145126056425.html, who report it.

In what seems a parochial story, the Herald’s article claims that Tsubo's founders think the Tsubi name is “too similar to their own brand name, established in 1998 and registered in Australia in March 2000”. So what we ask? Registering a name in a foreign market does not give necessary exclusivity, nor does it mean passing off as the name goes through domestic business name and trademark checks for any similarity. According to the Australian Securities and Investments Commission (ASIC) Tsubi registered its company name in November 2000 and its first trademark in 2002. Tsubo, on the evidence of our ASIC search, is not even registered in Australia as a business name or a company.

However, it seems that the matter is likely to play out in U.S. courts where, the Herald reports, that “after years of informal requests for Tsubi to change the name, Tsubo had started legal proceedings” against Tsubi in the Federal Court in New York. And surely this is perhaps where the money is and the real issue lies.

Also at dispute is the similarity between the two logos, with Tsubo claiming both brandmark fonts and logo design are similar. Interestingly, Tsubi’s logo is only registered in Australia for use on it’s newly launched sunglass range. Again, DIFFUSION wonders whether there is anything to dispute here. We know Tsubi only registered a mark for it’s eyewear label but otherwise the mark has been somewhat fluid (we couldn’t even find a definitive version on tsubi.com), so only have these two to compare.

The important thing is that both brands operate in distinct sections of the fashion market and while both are marketed and sold in Australia and U.S., any name confusion is going to have to prove some level of economic damage. It’s going to be difficult for Tsubo to prove that either its name or logo are being either traded-on deliberately by Tsubi or that Tsubi has deliberately copied aspects of the Tsubo logo as Tsubi’s mark, has been up to this time fluid and is not, as far as we are aware, registered for use in the U.S.

However, Tsubi, which probably has more of an international brand name to protect, would do well to look at both name registation and trademark registration in all markets it operates in and intends to market in, otherwise this action is likely to continue. Perhaps Tsubi’s owners are either being naïve or deliberately so?

22 March 2006

Newbridge look for value in Myer minus Coles.


New Myer owner, Newbridge Capital must have recognised something in the ailing Myer chain that others didn’t.

With an extremely modest $A60M estimated EBIT for this financial year, the $1.4B Myer sale price seems pretty high. However, Newbridge [www.newbridgecapital.com] believe in “unlocking value; recognising that value is often hidden in companies”. An item of great value that has been overlooked by Coles Myer Limited is the Myer brand. But "overlook" is perhaps not quite the right word as it implies neglect and Coles Myer can be accused of so much more than negligence.

Single-handedly Coles Myer has re-positioned the Myer brand to a place that has no resonance with its customers or communities, no differentiation from its competitors and no personality [see blog 8/2/06 ‘What’s the real value of the Myer in Coles Myer?’]. In addition, its heritage both as an intrinsic part of the Australian retail landscape, the community significance of the Myer family itself [thankfully now part owner] and in NSW, the richness of the Grace Bros. brand has been ignored [see blog 14/10/2005 ‘No one will save Myer now’].

Myer’s brand is valuable and with some TLC can be resuscitated. New Myer boss Wavish’s starting point of hearing “...what both the staff and customers have to say about the brand before we finalise any of our plans” [Sydney Morning Herald 13/3/2006], is vital. But what DIFFUSION would like to know is how this information is going to be collected, managed and translated into a real, meaningful and living brand?

Newbridge and Wavish need to treat the Myer brand as if it has been through a crisis [which in some ways it has], developing a brand recovery strategy that takes into account the past, the present and the future. The looking back and then forward process should uncover meaning and value that will stand the company in good stead for the long term – an imperative of Newbridge who “focus on investing in companies that have a sustainable long-term advantage over their competitors”. From this, a brand strategy should then be developed as an integral part of the business planning process, to place Myer on target to achieve their real potential of $240M EBIT [The Age 17/3/2006].

As we note in our previous NAB blog, the process of brand valuation is not achieved by a mere whip around to see what everyone thinks but is complex, overarching the whole of business and needs to be properly managed if it is to provide a real and lasting return.

NAB's new brand of wishful thinking.


Last month Australia's largest lender, the National Australia Bank (NAB), unveiled its revamped corporate logo and a new take on what is a decidedly uninteresting but functional name, 'nab'. Like most rebrands, NAB’s is no different - a redesign can cost millions, most of which is spent on standard roll out of a new mark. Buildings, websites and a whole lot of collateral, are reshaped and shredded to suit the new look (don’t get us started on the fact that even their new brochures still apply the superior case!). Cheques, letterheads, pens and business cards are binned and replaced. However, what is disappointing about this latest corporate makeover is how much it seems more of an attempt at papering-over the cracks in the organisation, than a radical re-envisioning.

One of the reasons cited for the rebrand was the NAB’s 2004 foreign exchange desk scandal, which saw it lose $360 million and consequently it’s CEO and much of its senior management team.

Interestingly some sections of the market have taken a completely different view of the makeover. Analysts seem to have a view that these kinds of spackfilla jobs “win no leverage”.

"The brand name and image is something that is more important to its customers - particularly retail customers. It's not a fact that is likely to drive a price-earnings model", said a Citigroup analyst quoted in the Sydney Morning Herald.

DIFFUSION finds comments like this somewhat disingenuous. Most company valuations always take an account of brand equity and in the case of NAB, there was a significant loss of equity when the FOREX scandal hit.

Traditionally brand valuation consists of four main strands covering fundamental financial and balance sheet analysis, contextual market and consumer analysis, brand analysis examining brand as a determining factor in the future earnings and the value accorded the brand and mark as intellectual property. A number of factors can be added under these headings and weighted according to their importance or relevancy. Consumer analysis, for example, should include customer satisfaction, brand preference, quality perceptions, value for money and good service while market analysis should include share of market, share of voice and growth statistics. Any financial analysis would include profitability, sales and margins forecasts. All of these can be combined to give total brand value and as such a price-earnings model does take account of the impact of customer sentiment on overall earnings.

Secondly, while NAB CEO Ahmed Fahour acknowledged during the week of the relaunch, "I've got the number one business bank in this country I've got the wealth management business. I've got a smaller but turning-around retail business. And the fact is that I can have one consistent conversation with you and we are all singing from one hymn sheet," there is also the need for organisations such as NAB to use their brand to be one of the determinants of their dialogue and interaction with customers. It’s not good enough to just trot out what is rather poorly realised signifier alongside the diminutive name; in NAB’s cade, the follow up to their rebrand, the new brand promise needs to be sold through the organisation.

When DIFFUSION talked to one of the nice NAB counter staff after the re-brand, they acknowledged that they had no real involvement in the process and didn’t know what what the new brand promise “We believe in people with ideas and dreams. Helping you fulfil yours is at the heart of everything we do” really meant.

So will customers see a different organisation and feel any different? Can a bank, or for that matter any institution or organisation, really help you to realise your “dreams”?

20 March 2006

Coles without Myer, still short on strategy.


Coles is now without Myer. Most market speculation is that the group will continue as before but with the capital inflow benefit of the sale used for other acquisitions, a share buy back or special return to shareholders.

DIFFUSION thinks one of the main reasons why Coles continues to lag behind Woolworths has been Coles' CEO John Fletcher’s inability and unwillingness to develop a coherent brand strategy for the whole group. As far back as 2004 Fletcher was telling people, like the ABC’s Alan Kohler, that he thought the group’s “brand strategy is something the rest of the world have already been to”, except it is clearly something that he hasn’t been to. In May 2004 DIFFUSION, along with a major Sydney advertising group, developed a group brand strategy as part of mulitmillion dollar pitch but was roundly dismissed by Fletcher as not a requirement for the company “right now”.

Now the same question IS being asked of Fletcher with market analysts in recent days wondering what’s next for the group. Sure, at this stage we don’t anticipate any radical renaming and there's not even speculation about that – it will likely become Coles Group and they will just redo the logo and the stationery (a quick flick across to the corporate website and they still haven’t dealt with the issue, a week after the sale went through) but we think it needs far more than that. Coles has blamed the worse than anticipated slow growth on “customer service problems at some of its supermarkets” (what service we ask?), fuel price rises and increased competition and promotional activity by Woolworths”. These seem to be excuses and illustrate how clearly Coles’ and Fletcher’s problem is one of strategy.

Now more than ever Coles needs to decide who it is. What is the brand? What does it stand for? How will it be described now that Myer is no longer part of the group brand structure? How any halo or gloss from the name Myer and it’s department stores association will change both customer and other stakeholder’s perception of the group? Of its existing companies, which will be lead brand vehicle for group? [There’s not a lot of sexiness in supermarkets.] These are important issues that need to be dealt with and not passed over. People never understood what Coles Myer stood for apart from a federated group of companies, now there’s even more reason for Coles to start working it out. Growth for growth’s sake is not enough anymore, expected sales growth of 9 per cent versus Woolworth’s 22 per cent might pull the fiscal heartstrings but it doesn’t sing anymore in the hearts of the customers. And that’s been the case for some time.

08 February 2006

What's the real value of the Myer in Coles Myer?


With a mooted $1b sale price likely for mid-tier Australian department store chain Myer, parent company Coles Myer has obviously taken its eye off the game. Its latest “All that I want” campaign launched this week, takes the embattled store (see blog No one will save Myer now) down to an all new low. Competitor David Jones' boss Mark McInnes has described Myer's heavy advertising and discounting campaigns as "irrational"”… but at DIFFUSION we think he’s being polite. With retail turnover continuing to fall in Australia (according to a Australian Retailers Association report in the Sydney Morning Herald 8 February 2006), Myer has obviously decided to continue its “irrational” approach by launching an expensive and brand damaging campaign. The full colour catalogue DIFFUSION found in its weekend paper seemed highly reminiscent of another ‘low budget’ Coles Myer brand, Kmart (see image above). According to Coles Myer, Kmart’s brand position is “low cost, discount department store” while Myer’s is “pleasurable shopping experience/service, great brands”. However, we're struggling to tell them apart. The new owners, whether CVC, Newbridge or Edgars, will not only have their work cut out for them in working out how much of the $1b is brand valuation, but will also have a long and expensive climb back up the slippery slope of re-asserting that value to investors, employees and customers alike, as Coles Myer has done a pretty good job destroying it.

P.S. The Kmart catalogue is on the left.

McKinsey & Co: we like it when the stars align.


McKinsey & Co (www.mckinseyquarterly.com) recently published their ‘Ten trends to watch in 2006’ and DIFFUSION was interested to see how many of their 10-year predictions matched ours, see blog Marketing futures: 10 brand and marketing trends for CEOs to watch in 2006. While our specific focus was on Australia, it is obvious as all Western businesses function in an increasingly global environment, companies here will experience similar challenges and opportunities.

Specifically six of our trends were significantly echoed in the McKinsey report: the separation between personal and work lives changing due to technology (trend 1); the emergence of Chinese brands (trend 3); the increased scale and reach of Government (trend 5); consumers becoming business participants with increased power and the growing importance of business ethics (trends 7 and trend 8); the importance of ritual and community for creativity (trend 9).

According to the McKinsey report they correspondingly identified that: “technological connectivity will transform the way people live and interact”; within the next 20 years economic activity will be equally aligned between Asia and Europe (with China and India being important players); “public-sector activities will balloon”; “the role and behaviour of big business will come under increasingly sharp scrutiny” (specifically the level of suspicion and acceptance from society towards big business will increase); the growing importance of communities, as these will increasingly “become responsible for innovations”.

The McKinsey article sums up by urging companies to look at the implications of these trends, especially in relation to their customer’s needs and competitive developments. DIFFUSION can't agree strongly enough with our colleagues at McKinsey & Co and have gone as far as making some practical suggestions for CEOs to consider. We might be visionaries but we're pragmatists too.

07 February 2006

Points of origin: putting premium beer makers in their place.


As we noted in our July 2005 blog Re:Place and the Specificity of Brands, place is becoming critical to the identity, authenticity and uniqueness (or the specificity) of a brand. Place provides an aesthetic counterpoint to the “generic” of the chain. The authenticity of a product, is determined by purity, tradition and the aura of history – all elements that are determined by place and which can both define and bring value to a brand. Yet, brand owners are willing to re/place and subsume identity, determining authenticity only by logo and thereby destroying uniqueness and hence value with an authorised non-specificity - all because, in the short term, it preserves margins and retains profit. To date consumers seem only to willing to go along with this charade.

A case in point is the tendency for domestic beer brewers to buy local brewing licences for international premium brands and then sell them into domestic markets labelled as “imported” brands with imported prices.

Let’s take the case of Sapporo. According to the Sapparo USA website (www.sapporousa.com) the beer has a brand built on distinct place and heritage values, dating back to 1876 with the founding of the Kaitakushi Brewery in Japan. The site says Sapporo's been in the US since 1984 and has established itself as the most popular Japanese beer imported into the US market (all true). Here we need to note the use of the word “imported” because in the case of Sapporo, the beer on the Premium Imported packs which loudly proclaims it is “imported” IS not from Japan but from Canada. Not even the water used in the beer is going to be same in Canada. Just as Sapporo itself makes Guinness beer in Japan for Diageo, it all seems rather incongruous and somewhat a case of a questionable trade practice with some long term implications.

So what’s going on here? We think we’re buying an imported beer with a brand heritage. We think the place of origin is Japan and we think we should be paying more for the specificity of the brand. The problem is that Sapporo, like so many other “imported” beers in the premium category, is engaging in what can only be described as authorised non-specificity, they are counterfeiting themselves.

Do customers care or even bother to read the label?

At DIFFUSION, we pride ourselves on thoroughness, so of course we read the labels. And we think it’s unfair consumers are being asked to pay premium prices for “imported” beer brands brewed domestically. Yet, according to an interview in Japanese Gourmet with Sapporo Beer USA president Mikio Masawaki, Sapporo still shipped over 2 million cases of beer in the US in 2005 and is now the US market leader by a wide margin.

Sapporo is a very simple and powerful example; but we’re finding this trend not just limited to beers, it’s in clothing and accessories, cars and other consumer categories. People are buying what they think is an internationally originated product but which is actually domestically produced or produced outside the place of origin. In the end, what will be the worth of place of origin, of national distinctiveness? What will be the point of difference? What will be the worth of the brand?

We think the idea of brand specificity is being overlooked by both brand owners and consumers. Brand owners need to carefully rethink current brand strategies built on strong customer recognition, derived from place of origin and manufacture. Consumers need to start thinking about why they are paying premium prices for products no longer attached to and manufactured in their place of origin.

What do we see coming? In many cases, consumer backlash against inauthenticity and a return to the type of purchasing behaviour that reinforces and supports genuine national identity and industry. It’s the reason why companies like clothing manufacturer American Apparel (www.americanapparel.net) are thriving. American Apparel now runs the largest garment factory in the United States, employing over 3,000 people at one location in a market where 96 percent of all clothing is imported. Strongly branded by its place of origin, locally manufactured and with sales projected at $400m from its 100 stores and overseas distribution, it proves the case for value in the point of origin.

News Ltd stumbles into a true local piracy debate.


TrueLocal (www.truelocal.com.au), the new Australian online search directory from Rupert Murdoch’s News Limited, seems to have stumbled at launch. The problem seems to be that a search directory sharing the same name was launched in Canada last November(www.truelocal.com).

It’s a case of either real ignorance on the part of News and its naming agency (if they even bothered to go through the process), commercial arrogance, or even a form of cyber piracy.

According to a Sydney Morning Herald report hundreds of Australians had already tried to sign up to the Canadian-based service, mistaking it for the same one offered by News. Even more serious is the claim by TrueLocal president Jake Baillie, who told the Sydney Morning Herald that News Ltd was made aware of TrueLocal's existence and expansion plans for Australia prior to the launch of News Ltd service. Baillie is threatening action.

DIFFUSION checked with Melbourne IT, a domain name registrant which lists truelocal.com.au as being registered by News Ltd on 14 November 2005, while a WHOIS.net search for truelocal.com sees it originally registered in May 2003 and operative from 15 November 2005. This means that the original domain name owners could assert their rights through the Internet Corporation for Assigned Names and Numbers(ICANN), which administers international domain names. Melbourne IT is an international registrant for ICANN and would presumably have an obligation to assert the original registrant’s right to the name.

According to ICANN’s policy on company name copying “disputes over entitlement to a domain-name registration are ordinarily resolved by court litigation between the parties claiming rights to the registration.”

ICANN’s policy states that once the court rules on who is entitled to the registration, the domain name registrar will implement that ruling. Where disputes arising from registrations allegedly made abusively (such as "cyber-squatting" and “cyber-piracy"), companys can then invoke a simple administrative procedure by filing a complaint with one of the dispute-resolution service providers.

At DIFFUSION we believe naming, which includes domain names, is not a haphazard process but requires careful domestic and international business and trademark checking. But when an international media monolith like News gets into some murky waters, we just have to wonder how much they really know.

The top logo is the true true local and the second is News Limited's.

18 January 2006

Marketing futures: 10 brand and marketing trends for CEOs to watch in 2006.


The start of each year for us at DIFFUSION is an important time for reflection…we normally look back at the year just past, write ourselves a report card and talk about and plan for the coming year. In this vein, we thought it would be good to share what trends we believe may be impacting business in 2006. Specifically, our focus is on brand, marketing and communications, but we believe the trends below have much broader implications, both personally and as business leaders.

1.TECHNOLOGY WILL DESTROY THE SEPARATION BETWEEN PERSONAL AND WORK LIVES

Technology will cause and enable overlap in our social, work and personal lives.

Example: Finding jobs is not an out of home activity, employees will do it at work. They are no longer dependent on newspapers but technology and social networks.
Implication: People will cache their time even though they will overlap it via their use of technologies.
Brand/marketing impact: More permission based and pull-marketing. Brands built around maintenance of whole-of-life will succeed.
DIFFUSION tip: Concentrate on more permission based marketing, focus on a whole-of-lifetime offer.


2. BRAND WILL BECOME MORE ABOUT BUILDING AND MAINTAINING EXPERIENCES AND LESS ABOUT MARKETING AND ADVERTISING


Increasingly brands will develop and survive by maintaining a long term relationship with customers, who are re-examining and re-evaluating products and services for value and usability.

Example: Casella Wines - non-traditional approach to marketing makes it No1 wine export for Australia and dominates US market. Reidel glassware - repositioning as the Wine Glass company creates illusion that wine is better drunk from its stemware and meets customer desire.
Implication: Key product differentiators will be not be what marketing employees and advertising agencies tell you but what your customers tell you.
Brand/marketing impact: Marketing and advertising will become less meaningful. If you don’t give customers what they want, someone else will.
DIFFUSION tip: Concentrate on brand strategy that encompasses a long term customer experience.


3. CHINESE BRANDS WITH THE POTENTIAL TO DOMINATE MARKETS WILL START TO EMERGE


China’s government has been preparing the top 150 companies to go overseas and expand. Over time China, like Japan, will change it’s image from cheap manufacturer to premium quality manufacturer at a value price.

Examples: Lenovo is now third largest PC maker in the world. Haier's bid for whitegoods manufacturer Maytag, would have given it 30% market share in the US. TCL is the world’s largest television manufacturer. China’s share of worldwide LCD market doubles in ONE year.
Implications: Via brand name acquisition, Chinese companies will gain access to global distribution markets, sophisticated R&D and recognisable brand names.They will be a threat.
Brand/marketing impact: Brand differentiators on price and quality will continue to erode, customers will go to the cheapest offer.
DIFFUSION tip: Develop stronger and more specific brand place and point of origin strategies for your business.

4.CUSTOMERS WILL NOT ONLY DISINTERMEDIATE YOUR INFORMATION, THEY CAN DISINTERMEDIATE YOUR BUSINESS

The demand economy gives customers the tools they need to demand immediate, personalised fulfilment whenever and wherever they desire.

Example: Personalisation offered by Amazon, Dell, eBay and TripAdvisor means we can customise, configure, self select, review and critique, buy, sell, trade and destroy businesses and traditional business models in one go. HMV in UK, effectively disintermediated itself within its own market.
Implication: Customers will find other retailers and suppliers if you don’t give them what they want, when they want and in the way they want. It’s more of a global market than you think.
Brand/marketing impact: Whole of brand experience needs to focus on satisfaction elements. Don’t ignore personalisation.
DIFFUSION tip: Develop customer advocacy within your business.

5. THE SCALE, SCOPE AND REACH OF GOVERNMENT WILL CONTINUE TO INCREASE

We are subject to increasing government scrutiny, not just in the guise of national security concerns, but in our everyday activities such as the cost of running and maintaining business.

Example: The Australian Public Service has grown by 16% since 2000. Capital spending on defence alone will be $52b in the coming years; Australia’s taxation laws run to 10000 pages and it costs $30b and 80000 people to defend and avoid it.
Implication: We will become increasingly isolationist, defence will continue to eat up government spending and against the grain of globalism the idea of national sovereignty is being emboldened and becoming increasingly jingoist. Personal freedoms and the ability of business to operate freely has become more difficult. We are now subject to more red tape than ever.
Brand/marketing impact: Opportunity to provide more 'protection': brand messaging; products that lessen bureaucratic impacts
DIFFUSION tip: Concentrate on messaging that provides safety and security messaging. Traditional and Australian is good.

6.TRADITIONAL MARKETING MANAGERS ARE DEAD

Marketing Managers roles are diversifying and changing to the point where their validity needs to be questioned.

Example: Executive marketing section of seek.com only listed 16 of 74 jobs for marketing managers.
Implication: Selling has become much more complex and diverse expertise is required across increasingly specialised areas.
Brand/marketing impact: True marketing departments will no longer exist, businesses will need to be more flexible employing a range of ‘experts’.
DIFFUSION tip: List what skills your business needs, assess your Marketing Manager and put in place strategies for accessing experts you really need.


7.CONSUMERS WILL BECOME PARTICPANTS IN YOUR BUSINESS


Consumers are becoming increasingly participant in business, but there is a catch.

Example: Participant consumers have increased power through the internet, consumer protection laws and access to mass media.
Implication: Unhappy participant consumers can do your business major damage.
Brand/marketing impact: Honesty, scrutiny and open communication are vital.
DIFFUSION tip: Don’t just have a complaints policy, have a meaningful and closely tracked customer feedback process in place.


8.ETHICS WILL CONTINUE TO GROW AS A PRIORITY

Historically, aiming for shareholder satisfaction has meant that ethics takes a back seat…not any more.

Example: Strategy + Business magazine, ethics voted third most important concept of last 10 years. Practicing ethical communication has been stated as the “greatest challenge in the 21st century”.
Implication: The public, broader community, employees and business itself is demanding that companies act ethically.
Brand/marketing impact: Changing role of those responsible for communication in your organisation.
DIFFUSION tip: Allow communication (and marketing and customer relations managers etc) to provide real advice and critical feedback; don’t make them simply corporate mouthpieces.


9.RITUALS ARE BECOMING INCREASINGLY IMPORTANT (AGAIN)


Increased secularisation and loss of community has lead to a need for rituals.

Example: The rise in urban or consumerist rituals spread primarily by the mass media.
Implication: These rituals sustain, but do not transform. What we need is 'communitas' – a social structure based on common humanity, not hierarchy – brought about by liminality.
Brand/marketing impact: Liminality, a ritual of change, contains, according to theorist Turner “the seeds of the future.”
DIFFUSION tip: Seek to encourage opportunities for liminal events in our organisations and encourage those who are creative thinkers. Richard Florida also has a lot to say on the role of creative thinkers within society.


10.FIRST CAME PUSH, THEN PULL, NOW ADVOCATE


Push marketing, replaced by pull marketing or push/pull combinations is being replaced by customer advocacy.

Example: Due to growing customer power and lack of response to traditional marketing models, Glen Urban is urging a model of advocacy… “truly representing your customers’ best interests”.
Implication: Advocacy will become the norm for business behaviour, if your not practicing it, your competitors will be soon.
Brand/marketing impact: Review of much more than your CRM system…this trend requires a major overhaul in approach.
DIFFUSION tip: Look for ways you can provide open, honest and complete information to your customers now, including products that are not yours!

The future is hard to predict…and we don’t recommend the fortune cookie method as a way to plan for business. A way forward is to sit down in your business, pull together a cross section of employees (people whose opinions you trust) and brainstorm what trends are going to impact you and how you are going to tackle them both as threats and opportunities for the future.

This formed part of a presentation to the CEO Institute of Australia, 17 Januray 2006. For the full text of this presentation email ideas@diffusion.com.au
11 January 2006

Is it time for airport cinemas? You could ask Mark Cuban.


The New York Times recently published an article on Mark Cuban’s Landmark Theaters in its Digital Domain section. Entitled “Is Mark Cuban Missing the Big Picture?”, the article amounted to a mild (?) condemnation and questioning of Cuban’s dedication to digital cinemas. While Cuban, with a net worth estimated by Forbes at around US$1.8 billion, might “enjoy the presumption of possessing impeccable credentials as a business strategist and a technology futurist”, his foray into digital cinema is under question by the industry.

Not only do we belive Cuban is on the right track, we think he could get even bolder. The digital cinema market is about to get even bigger!

Around the globe airports are seeking to meet the ever increasing demands of transumers for new airport leisure experiences that mirror non-travel experiences. In addition, cinema advertisers, exhibitors, distributors and content providers are looking for untapped market segments that delivers growth similar to their entry into shopping malls/centres in the 70s.

DIFFUSION has been working on a digital cinema project with a select group of cinema and entertainment industry veterans for the past three years; approaching and meeting with a wide variety consultants, private equity firms, venture ca italists and suppliers in Australia, the United States, New Zealand and the United Kingdom to develop an extensive business case and plan.

We call it CINÉAIR (www.cineair.com), the world’s first airport cinema chain.

CINÉAIR is based on the current cinema multiplex model and much like Cuban's approach, each multiplex includes a number of fully automated digital cinemas. The big difference is that CINÉAIR cinemas are located AIRSIDE at selected international airport hubs, delivering a potential market of 8.5 billion people annually (1.2 billion more than the entire global cinema market). Cinema entry is via a self automated kiosk and turnstile system, priced on a Pay-Per-View (PPV) basis or through a Pre-Paid arrangement with major airlines, so it can be incorporated into airline tickets [...we note with interest that the EU has ruled that from February, airlines landing within the EU will need to provide meals and other compensation for delayed flights]. CINÉAIR Programming includes first-release major motion pictures and location-specific (i.e. tourist information services) or time-sensitive programs (i.e. major sporting events).

CINÉAIR is in the final development stage. We’ve been seeking an investor/s to help us develop the initial infrastructure and to launch the first site. We’ve done all the spade work, run the investment scenario, the development costs and the forecasts [...with attractive returns within five years]. Finally, we know which airports it can run in, we’ve identified them and we know many airports are already forseeing cinema as an important part of the new development mix for the future of airport retailing.

After the New York Times article we contacted Mark through his blog http://www.blogmaverick.com/ The maverick is yet to respond. Can you let him know we hoping to hear from him soon..

Are we wired for brand choice?


According to a new study by California Institute of Technology, reported by New Scientist our liking for a particular brand name could be wired into a specific part of our brains.

Using new neuroimaging techniques Caltech identified two regions of the brain – the ventral striatum and the ventral midbrain – as having an important role in identifying our preferences for particular products based on our access to previous learning.

“The key message of our study is that we are able to make use of neural signals deep in our brain to guide our decisions about what items to choose, say when choosing between particular soups in a supermarket, without actually sampling the foods themselves,” study leader John Doherty told New Scientist.

“This is because we can make use of our prior experiences of the items through which we fashioned subjective preferences – do I like it or not?”

“The next time we come to make a decision we use those preferences.”

DIFFUSION believes the study has important repercussions for our understanding of how our first experiences and exposure to products and services can be deeply ingrained into our behaviours and therefore our responses and choices.

More importantly, it means companies and businesses need to address consistently, the total brand experience of customers and clients. It signals a warning that later attempts to alter or modify brand experiences through the use of public relations and advertising, may have no effect whatsover on these first impressions and experiences.

02 November 2005

What kind of marketing does your organisation really think it needs and how do you get it?

What kind of marketing do you need? What kind of marketing do you do? It’s been our experience working with both small and large businesses, that often a company might want to undertake a marketing program but is not really prepared for it...as a result some works gets done but it is never effectively implemented and no one feels the program was very successful. Why?

It’s an interesting question and one that US business consultants Booz Allen Hamilton and the US Association of National Advertisers recently worked on together. What they did was to define types of marketing 'organisations' that already exist within most businesses today. Their report identified six distinct types of marketing within organisations. According to the study, all have unique strengths and each is appropriate to particular types of companies in certain competitive circumstancesvalued within the company for its ability to drive revenue. It is considered as important as other major departments, such as finance and sales. It drives the company’s priorities and leads product innovation and new business development.


1. Growth Champion. The marketer is highly valued within the company for its ability to drive revenue. It is considered as important as other major departments, such as finance and sales. It drives the company’s priorities and leads product innovation and new business development.


2. Senior Counselor. Functioning as a high-level advisor on marketing strategy to the chief executive officer and the individual businesses, the marketer is the Senior Counselor, leads major advertising, promotion, and public relations campaigns. Unlike the Growth Champion, however, it does not typically drive company-wide strategy.

3. Brand Foreman. The marketer is an efficient provider of marketing services, ranging from communications strategy to creative output and campaign execution, in support of the company’s key brands. It serves as the central manager of agency relationships, and is considered among the company’s most important support organizations.

4. Growth Facilitator. The marketer has the authority and skills to develop and lead large, company-wide marketing efforts and helps set the business’s overall priorities. They coordinate with other major functions, such as sales and product development.

5. Best Practices Advisor. The marketer works with the individual businesses to identify internal and external best practices and incorporate them into all marketing activities. This organization’s goal is helping the businesses achieve maximum effectiveness and efficiency, and it has expertise across all elements of the marketing toolkit.

6. Service Provider. The marketer supplies marketing services such as advertising, promotion, and public relations at the request of the company’s brand and product teams. The Service Provider is effective at executing specific tasks and is responsive to time-sensitive requests.

According to the study, many companies with internal marketing functions claim to fulfill most or all of these, but in reality they tend to gravitate to only one of these roles. DIFFUSION believes that knowing which type of marketing function exists within your company is critical. The challenge is to understand where the company is heading and make sure marketing is developed and configured properly.

More importantly, we believe that it is the absence of brand and marketing capability, in any form, in many organisations which is far more critical and one that the Booz Allen/ANA study does not consider. Where this type of function and the culture associated with it is missing or where it is relegated to a partial consideration and/or a part-time role, this seems a fundamentally more important place to start.

So we’ve added one new type of marketing for organisations.

7. Consultant Provider. In the absence of a real marketing organisation, an agency or consultants supplies brand and marketing services such as strategy, advertising, promotion, and public relations at the request of the company’s management. The Consultant Provider must be effective at executing specific tasks, is responsive to time-sensitive requests and often provides this on an on-going basis.

20 October 2005

The defining essence. Getting a handle on Oroton.


Australia’s Oroton Group as Australia's only luxury clothing and accesories group, used to be a bellwhether for contemporary Australian luxury but not any more.

At the turn of the century, the company began an aggressive acquisition program that saw it acquire the Morrissey and Marcs brands. At one stage both of these brands were originally positioned at the higher end of the Australian fashion market, Marcs used to import leading European designer brands and Peter Morrissey, alongside long-time partner Leona Edminston, used to sell into New York department stores. Since 2003 the group has shown static growth, with both the Marcs and Morrissey brands subject to constant revision and somewhat arbitary repositioning. We think we might have some idea why the Oroton Group might be getting it wrong.

This is Oroton’s customer segmentation model from a recent presentation:

Oroton
Contemporary consumers who spoil themselves and others through quality purchases

Polo Ralph Lauren
Quintessential classic contemporary shopper

Polo Jeans
Classic youth minded shopper

Marcs
Contemporary consumers who seek quality fashion

BabyDoll
Fashion driven youth-oriented shopper “Gotta have it now”

Morrissey
Sophisticated consumers who value individuality

Aldo
Fashion aware, on-brand shoppers who place price and quality as paramount

The interesting thing about what these descriptors reveal is how little Oroton seem to know about their customers, interchanging the word “shopper”, “consumer” and “individual”, without really attaching any single unique detail or benefit to purchase. Instead, they use ambiguous outcomes like “quality”, “ value individuality” and “contemporary” in a naive attempt to segment their customers. All seemingly simplistic, almost as if they are frightened to actually say who their customers are. More importantly, we believe the poor performance of some of these brands can be attributed, not to a flat trading environment which the group cites, but to their failure to actually understand and get inside the minds of their customers.

One of the opportunities we see for Oroton is the adoption of a more benefit-based market segmentation approach for their portfolio. This involves segmenting the market for their products across all the brands and introducing a brand lifecycle based on the intrinsic value that their customers get from their products, not by traditional conjoint analysis, which identifies customers on variables such as how much money she makes or where he lives. This intrinsic value (benefit) could take various forms such as the snob appeal of Polo, the perceived quality of Oroton or the derived economy in an Aldo shoe customer.

This method of market segmentation is significantly different from other methods of market segmentation in use. It gets inside the consumer’s thinking and finds out what the customer feels about a product or brand. The underlying principle is that consumers do not seek a product or brand, rather they seek alignment with a brand essence - they want what it does for them, or the derived benefit – how it makes them feel, look and the status they get from the purchase. With benefit-based segmentation, the objective is to identify why the customer is buying the product, and group customers accordingly.

Oroton Group currently seems to see the outward benefit of segmentation as a way to market to customers within the brand portfolio rather than across it. However, using a benefit-based market segmentation model, the objective is to group customers together for the most effective targeting, not separate them out to be targeted separately. Something that fits with the Group’s recent stated goal to adopt a “whole of company” approach to their brands.

14 October 2005

No one will save Myer now.


It comes as no surprise to hear that embattled Myer is pulling out all stops with a new Christmas advertising campaign [Sydney Morning Herald 12/10/2005] in the lead up to its fire sale by parent Coles Myer Limited [CML]. Even more telling is the heat around the corner from a falling share price.

There have been a number of tell tale warning signs, all of which both CML boss, John Fletcher, and Myer MD, Dawn Robertson, have either ignored, misread or more likely, simply not noticed. Part of the problem stems from a greater issue, to do with CML and its inability to understand brand, both at a corporate level and at an individual business level. Secondly, like many other corporates, CML continues to relegate brand strategy to advertising agencies, who roll out tvc and print campaigns that do little to build brand in a way that is committed to integrity and longevity. Thirdly, CML has lost its ‘reason for being’ beyond that of economic rationalism [which is taking a beating anyway!]; yes, they provide millions of products to millions of Australians, but aside from this functional attribute, CML, our largest Australian company, doesn’t stand for anything in our hearts and minds.

Which brings us to the specific problem of Myer. I grew up in Queensland and as such, am familiar with the Myer brand. Intrinsically Melbournian [as evidenced by their choice of spokesperson Barry Humphries, about as much of a Melbourne icon that you can get], in Brisbane, that didn’t really matter…Melbourne represented a culture we didn’t have; it was aspirational, European, stylish, black and white, classical. However, Sydney was a different story. The move in 2004 to replace the iconic shopping brand Grace Bros with Myer, was always going to be problematic. Not only because Myer wasn’t NSW or more importantly ‘Sydney’, but because Grace Bros provided differentiation to David Jones [who can tell the black and white sales ads in our newspapers apart?] and had a significant and meaningful brand heritage.

In 2004 I co-authored a joint research paper examining the loss of the 119 year old name, Grace Bros. The paper, 'Out of the Red into the Black' [Murphy, Ringma & Jetland] examined the narratives [or stories] of both Grace Bros and Myer. It found that ‘Grace Bros played an important role “as a rhetorical interface between organisational culture and organisational identity” (Faber, 1998), an identity that had resonance in the community beyond its role as a retailer’. The research found that CML over 16 years of ownership, had systematically removed the history of Grace Bros and its related stories, ‘representing a deep disconnect between the current organisation and its narrative, cultural and value history’. It was a history and stories which customers, both young and old, continued to relate to, regardless of their attraction to Robertson’s “newer, brighter better” mantra.

It is now too late for Myer and one only hopes that CML has learnt some lessons, so that it won’t all be in vain. It’s unfortunately apt that the latest Myer catalogue is headlined, “Big, black bag”, all too reminiscent of a body bag they use for the newly departed.

Photo: John Woudstra. Courtesy Sydney Morning Herald 12/10/05.

10 October 2005

Place branding. Are they serious, Mum?


Want some elementary school kids to name your suburb? Any takers for Pokemonville? Disney? Nelly? This is what the NSW Property Council in Sydney wants to see happen following a decision of the State Government to rename an area east of the city after the popular entertainment precinct, Darling Harbour.

The Council is up in arms because they believe that branding "East Darling Harbour", a 22 hectare site in an area formerly called Millers Point, will be difficult under the proposed name.

According to one Sydney Morning Herald report, NSW Property Council executive director, Ken Morrison thinks the name will be regarded as something of a last minute tack-on; both meaningless and not memorable, just convenient for untaxed imaginations.

“East Darling Harbour sounds like its left on the edge of something else", Morrison is reported as saying and thinks elementary school kids could come up with a better name.

As we note in our 21 June blog Place branding. Not so new., both the naming and branding of distinct urban areas is something that is serious and should be performed by professionals in consultation with the local communities. And anyway, what was wrong with Millers Point?

Meanwhile, the State Government says they will listen to proposals. We think given the Minister’s reputation, nothing much will happen.

16 September 2005

Doctoring language.


Recently seeing a new doctor for the first time with my sick teenager, [our regular GP was away], I was taken aback when halfway through explaining a short history of what had been happening, he interrupted me mid sentence with, “do you mind if I ask the questions?” [with a tone of voice that indicated he didn’t give a rats if I minded or not]. A communication approach I had experienced several times prior to finding my current [and beloved] GP, I had forgotten how debilitating ineffective doctor/patient communication can be.

While there have been some moves to ensure that doctors leave the education system with adequate communication skills, unfortunately, there isn’t enough emphasis from the Australian Medical Association (AMA) and related professional bodies, on the importance and provision of skills for effective doctor/patient communication.

The current communication practice of many doctors is best described as ‘ethnocentric’; a view of the world where members of their own group [other medical and related health care practitioners] are valued and understood, while nonnatives/others [patients] are as seen as “fundamentally different and therefore deserving of different treatment” (Grimes & Richard 2003). While this, in and of itself, isn’t necessarily a problem, ethnographic communicators “develop simplified scripts in situations that necessitate interaction” (Grimes & Richard 2003), scripts which function to keep nonnatives [in this case, patients] predictable and within interaction limits. This leads to the sort of communication behaviour I was subject to.

Doctors need more than empathy in their doctor/patient relationships. I believe that they need to practice ‘cosmopolitan communication’; communication in which “others are treated [simultaneously] as both native and nonnative”. Importantly, cosmopolitan communicators understand and appreciate the genuine differences between groups, treat others as fundamentally like themselves and accept that “ways of understanding are open to change yet exempt from change” (Grimes & Richard 2003).

Neuworth (2002) in an important article in the Medical Journal of Australia, ‘Reclaiming the Lost Meanings of Medicine’, advocates doctor/patient relationships that are “intimate, sometimes gut-wrenching”. He states, “We need to create an ongoing public dialogue around the relational and ethical aspects of healthcare.”

Perhaps the practice of cosmopolitan communication may be a start. And maybe we could also encourage our accountants and other personal and professional advisors to do the same?

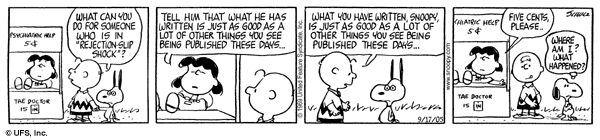
Image courtesy http://www.peanuts.com/ The Offical Peanuts website.

16 August 2005

Silver is so turn of the century.


Mercedes Australia is putting paid to their own lack of diversity in car colours, particularly our love of machine age silver.

According to the latest edition of their magazine for car owners, we are going to start turning away from our obsession with turn of the century silver to reveal it’s more subtle hues - see a reversion to soft turquoise and light green-ish yellow. Even the ubiquitous colours of Calvin Klein beige and shades of brown will find their way onto our roads in the next three to five years.

According to BASF coatings, we’re “yearning for the familiar” and with that will be a range of colours associated with deep blues, green tones, creamy beige and warm reds and perhaps, even gold. BASF describes the trend as move to towards spontaneity and luxury.

If luxury car makers are acknowledging the move, then we are likely to see many of these colours begin to appear on a range of electrical and portable appliances as consumers seek more opportunities to express both their mood and their individuality.

Meanwhile New York Fashion week claims black is back. They say we’re sick of pastels, bright colours and the boho look.

But really, when was the last time you saw a brown car??

02 August 2005

That's my line.

deniro2

The July 28 New York Times reports a California businessman has filed a lawsuit against American Express, claiming they stole his tagline of the company's "My life. My card." (see DIFFUSIONBlog 01 February 2005 “This is not My Card”).

While American Express has maintained in court filings that it owns the legal rights to the slogan, lawyers for the businessman Mr Stephen Goetz, a credit card marketer in San Francisco, plan to subpoena evidence from American Express' advertising agency Ogilvy & Mather.

The issue is who owns the line and whether American Express independently conceived the idea for the campaign that began in November last year, or took it from the businessman Mr Goetz, who claims he used it in a sales pitch to the financial services company in the previous July. Subsequently, American Express spent more than $88.9 million on credit card advertising in the first quarter and according to TNS Media, much of that featured the line "My life. My card." .

The various counter claims in the court filings has Mr Goetz claiming he provided the slogan to American Express on a proposal in July 2004, Ogilvy did not run the campaign until November 2004 but claim they registered the strapline as a domain name in September that year (the article doesn’t say what the domain name Mr Goetz was and whether it actually exists). Mr Goetz also claims he registered the line with the US Patent Office in September, while American Express claim they registered it a week later.

At DIFFUSION we believe the ownership and origin of taglines, straplines and slogans can be a contentious area for companies and businesses. The important thing for owners and their agents to do is to create an extensive and registerable paper trail for the development of the name, register what is registerable and steer clear of the generic. In many cases, similarly worded and generic taglines, straplines and slogans, often used and trademarked by different companies operating in different business areas, are tolerated as long as they are seen as markedly dissimilar in look and feel.

The problem for American Express, Ogilvy&Mather and Mr Goetz is to be able to sufficiently demonstrate an origin and ownership papertrail and we’re left wondering if any of them actually can.

29 July 2005

Branding ambiguity.


Gandell Properties has launched “The Entertainment Quarter” along with a snazzy logo as the new name for the Fox Entertainment Precinct out at Moore Park, Sydney. The question is was it ever formally identified as this or was it just called Fox Studios or the Sydney Showground? We think the latter. The ad (SMH July 19, 2005) and the need for any type of promotion of this is even more interesting. If there was ever a need for a more formal strategic brand planning, this project needed it. The naming is a mess. The website (www.entertainmentprecinct.com.au) describes the suburb of Moore Park as a “precinct” and the Fox Studios as a “creative campus”. In addition, the area also plays host to a number of other venues including the so badly named Aussie Stadium, the Sydney Cricket Ground, the Royal Hall of Industries and the Hordern Pavillion. So the problem is exacerbated by trying to overlay what is really quite a generic name over what is rightly indentified as a precinct in it’s own right. Within this precinct there are distinct destinations and so the name is meant to provide some point of unity, some way of providing a natural self identification for the area.


When DIFFUSION worked with Lee Wharf Developments, Honeysuckle Development Corporation and Crone in Newcastle we benchmarked numerous world projects that had attempted to define and name specific work and play precincts. The problem is that names are resonant things and they are generally accorded status and recognisability through usage. One of the problems faced by Lee Wharf Developments was what was to call a large site which had already been embedded with multiple associations and uses. We came to the conclusion that like most place brands, the recognition, use and common association of a name by the stakeholders of a place needed to be acknowledged. So we worked back to the original name for the site and developed a brand strategy that gave the whole place ONE name with internal alphanumeric naming for individual buildings and recommended historical or geographic names. We called it Lee Wharf Newcastle because that’s what it was called and where it was. Interestingly the word "Newcastle" was an important addition as Lee Wharf did not, just as the word "the entertainment quarter" does not mean anything without a place holder.

We also invoked the work of Richard Florida, who has made significant contributions to latest thinking on the value of creative culture in recognising, identifying and valuing place. We took Florida’s term “the quality of place” and built a evolutionary and dynamic brand strategy around this that enabled all stakeholders to participate at Lee Wharf.

While the idea of naming this Moore Park entertainment precinct is excellent, the name and logo itself is so generic it lacks specificity and association. The visual articulation of the name, while strong and vibrant, is in itself generic. The use of the sectional quadrant while suggesting part of a whole, never really comes to grips visually with what whole it is describing. It’s merely an amorphic image.

And it’s a shame. A great opportunity to create an evocative new place that will largely go ignored except by the people who did the work because of this lack of meaning and association. Merely another poorly strategised branding exercise.

20 July 2005

Do we need new symbols of National Interest?

Ausmadeswngtag Ausowned&madelogo waowned ausmade_logo

A recent set of comments by writers to David Dale’s July 12 column www.smh.com.au/articles/2005/07/11/1120934178159.html “How to Australianise”our supermarkets in the Sydney Morning Herald attracted our attention. Dale was commenting on the ability of consumers to buy Australian made and owned products in the nation’s supermarkets. Consumers willingness and ability to buy these types of products is more important these days given Coles Myer and Woolworth’s duopolic dominance. With 70% of the Australian market, they remain the most dominant supermarket retailers in the world and a cause for concern by both consumers, the Australian Competition Commission and competitors alike.

We took a look at the Australian Made site www.australianmade.com.au to see what constitutes an Australian made brand. According to Australian Made, “the Australian Made logo is a registered certification trade mark. To qualify to use the official Australian Made logo, products must comply with the country of origin provisions of the Trade Practices Act. Australian Made products must be substantially transformed in Australia, with at least 50% of the cost of production being incurred in Australia Licensees of Australian Made products must have a current licence agreement with Australian Made Campaign Limited; and agree to abide by the Australian Made Logo Code of Practice.”

Australian Made’s own 2002 research suggests that “the green triangle and gold kangaroo logo is the most recognised country of origin symbol on Australian shop shelves, enjoying a 96% recognition level amongst Australian consumers. With nine out of 10 consumers saying they have purchased goods carrying the trade mark and 66% say they actively seek out products that are made in Australia.” This is not backed by what the SMH commentators say, most want to see more publicity on what constitutes Australian made and owned. They are confused by the plethora of logos and marks and it seems that, on the face of it, the Australian Made logo does not enjoy the recognition it claims.

As we note in our previous blog on the specificity of brands, more accurate Place of Origin branding would make it easier for consumers to choose Australian made and owned brands and would perhaps force retailers to stock more of this Place of Origin product. German supermarket company Aldi has established a considerable beach head in Australia and already uses the “80% Australian made ” as a point of difference, but the new Woolworth’s Select range (a name we know was “copied” from Tescos Supermarkets in the UK) and the new premium GC Coles brand would also be perfect vehicles to adopt the Australian made and owned branding.

One of the problems with endorsing brands like the Australian Made logo is that it is not an absolute benchmark and thus can create a tendency towards ambiguity about ownership. While Australian Made rightly makes the point that people can feel more confident about products that carry this logo, the evidence from the small sample of comments in Dale’s article is that people do not necessarily trust this and other words carried on packaging. They’re looking for a recognisable symbol of both aspects of Australian production and ownership. More importantly, we believe that Australian Made should be raising its limits on what constitutes an Australian made brand and sponsoring a move to an an absolute benchmark for Australian made and owned. 50%+ production in our mind does not constitute this and from the SMH consumer comments, the use of this symbol continues to reward those companies that are no longer Australian owned.

14 July 2005

Replacing place, the specificity of luxury brands.

madeinchina

Many luxury brand customers have developed an almost arcane adherence to the brand values of uniqueness and authenticity derived from place. It is the ostensible idea of an historic solidity, a departure from the more peripatetic attention to fashion and seasonal remodelling of consumer brands, that serves to distinguish the specific identity of luxury brands. Many luxury brands rely on the fact that they do not look externally for inspiration, that they only need look to their place of origin, of manufacture. Place, whether it is Tuscany or London, is what DIFFUSION argues contributes to the soul or essence of a brand and delineates it. So what happens when a luxury brand decides that place is no longer such a source of inspiration?

While consumer brands everywhere continue to seek to manage ever diminishing margins as they ride the wave of affordable affluence, luxury brands across all categories have, or are considering, moving manufacturing to global factories like China for much the same reason as their lesser counterparts.

Interestingly the move to “Made in China” seems to be coming from the franchisees of many of these luxury brand owners, rather than brand owners themselves. While many luxury brand owners such as JPTodd have avowedly rejected outsourcing manufacturing, others have embraced it. This new place label “Made in China” is already being borne by a swath of companies in Europe and the US, including Steiff, Coach, Kate Spade, Paul Smith and Armani, who have already shifted some of their manufacturing to mainland China. In Australia, much of the Oroton Group’s stable of brands has already migrated to the far east. And according to Bear Sterns it’s a trend that is showing no sign of abating. For example, they estimate that by 2010, 50% of all US manufacturing could be outsourced and the new place of manufacturer is likely to the be the global factories in China and India.

Which begs some questions: Do companies confuse country of origin with country of manufacture and believe their consumers can’t tell the difference? How will consumers be able able to tell the difference between the output of brands all manufactured in the same country? What will the nuances be? What do they believe consumers are motivated by – product or price? Do they only see value displayed by logo and name rather than quality? How do they value their brands on the balance sheet? What risk assessment do firms make of the effects on the brand associated with outsourced manufacturing? What account do they make of the the risks inherent in sharing manufacturing techniques and skills with potential competitors? How can product delineation and quality be preserved in the global factory?

For luxury brands the idea of place is critical to the identity, authenticity and uniqueness (we call this the “specificity”) of a brand (otherwise why would counterfeiting exist?). Place provides an aesthetic counterpoint to the “generic” of the chain. The authenticity of a product, as Virginia Postrel notes in her book The Substance of Style, is determined by purity, tradition and the aura of history – all elements that are determined by place and which can define a luxury brand. Yet, these brand owners are willing to re/place and subsume identity, determine authenticity only by logo and destroy uniqueness with an authorised non-specificity (authorised counterfeit) - all because it preserves margins and retains profit.

We think the idea of specificity is being overlooked by many brand owners and demands a careful rethink of current brand strategies, built on strong customer recognition derived from place of origin and manufacture.

Photo copyright Amanda Tsui 2004 Pratt School of Art, New York City

22 June 2005

Crocodile Dundee Man unearthed again.

crock_dundee3

We were interested to find out from Saturday’s [18/6/2005] Sydney Morning Herald that according to Dr Clotaire Rapaille, a self styled marketing guru and “cultural psychologist”, Australian’s can be defined by the “key word”, “invincible”. Dr Rapaille says we are tongue in cheek Crocodile Dundee men, due to our origins [think convict settlers], our participation in various wars and, of course, “the bush”. Whether or not his views are based on any actual research, Jungian style, or simply his own deduction, the article does not make clear. ‘Crocodile Dundee Man’ is an archetype that we would like to see the early death of, not because it is outdated, or because its sexist, or because it is an artificially created Americanised version of Australian national identity, but because it is simply incorrect.

As Hugh McKay so rightly points out in the same edition of the SMH, “our identity is still evolving and we’d be foolish to try and define it prematurely”. We would like to think, together with McKay, that we side a little closer with Canada [even if we do lock our doors in some suburbs of Sydney] who completed the statement “as Canadian as...” with “...it’s possible to be in the circumstances”.

Yes, we are undergoing a time of self assessment - what does it mean to be Australian? Or, for that matter, un-Australian. But this is all part of our coming of age. Hopefully our sense of humour will not be lost when we finally get there, though I’ll be happy to plant a cross on the grave of Crocodile Dundee Man sooner rather than later.

21 June 2005

Place branding. Not so new.

SYDNEY

We were recently sent an article by a Canadian contact from enRoute magazine [‘This Brand is Your Brand’] on the ‘new’ profession of place branding. Not so new, we say. Place branding, whether a country, city, region, suburb or development, has been here for some time. Consider this 1938 quote, “A great city goes out beyond its borders, to all the latitudes of the known earth. The city becomes an emblem in remote minds; it exerts its cultural instrumentality in a thousand phases”. While we now have a more formal approach, the development of place brand strategies, understanding places as brands is not really new...we just now want to overtly manage them, or in some instances, such as a recent project we completed in Newcastle Australia, create them.

But yes, there is more discussion about places as brands. In part, this is because we are starting to more fully understand the holistic nature of brands but also because as people, we are now defining ourselves by where we live. Some interesting research has been undertaken to support this by Richard Florida, ‘The Rise of the Creative Class’, Professor at Carnegie Mellon University.

A true sign of the longevity of place branding is the recent outbreak of place brand generics...MCentral apartments in Sydney, recently claimed “genuine New York apartments”. The key is that even to those who have never been to New York, a style, emotion and mood is evoked by use of the term “New York”. Place branding can also be used effectively to re-generate an ailing geographic area. Parramatta Australia tried this in 2002, only to be thwarted by town planning problems.

What is vital, as with all branding, is that the brand is not artificially created, but is based on research and reality. When undertaking place branding for Lee Wharf Newcastle, we conducted multiple site visits, interviews with Newcastle residents [the true owners of a place brand] and lots of ‘digging’ in the historical section of Newcastle library. Place branding is also subject to the co-authoring processes of its inhabitants, who over time, assist in the shape and fashion of the place brand.

enRoute also refers to the importance of change in regards to place brands and even national identities; “radical thinking about our national futures is precisely the mindset required”. Which only supports Florida’s argument that “quality of place” is closely linked with our view of ourselves, hence we now define ourselves by where we live, not what we do.

Satellite image of Sydney copyright NASA 1996

08 June 2005

Not the end of print.

endofprint

In 1995 American designer David Carson famously declared the end of print. Not so, it seems somewhat resilient as a media form. According to TNS Media Intelligence, US advertising spending in major media in the first quarter of 2005 increased 4.4 percent to $33.5 billion from $32.1 billion in the same period last year with the major focus still on print. Local magazines led all media categories in percentage growth, rising 26.2 percent to $103.7 million from $82.2 million. By total dollar amount, local newspapers led the categories, at $5.869 billion, followed by broadcast television, at $5.845 billion.

Is this signalling a change back to more personal hands-on media? Certainly the trends in Australia reflect more of a prediliction for media planners to focus on electronic media.

According to the Magazine Publishers of Australia, media spend estimates here for 2005 vary from a low of 4.2% to highs of over 11%.

Media agency Zenith predicts the Australian ad market will grow by 5.3% in 2005 with the internet leading the way with an estimated 30% increase in ad spend to $390 million (compare this with the US magazine increase of 29%).

Zenith predicts television and radio ad spend will grow by 5% followed by magazines (4.4%), newspapers (4%) and outdoor (3.7%).

Consultancy firm PricewaterhouseCooper predicts in a range from 4.1% to more than 10%, while Citigroup analysts predicted only a 4.2% increase in ad spending in 2005.

Perhaps Australia is a less literate nation than we pretend to be, or maybe it's because advertising agencies see the lure of more $$ in electronic media than print, and steer their clients appropriately.

So we are a little ahead of the US in terms of spend but perhaps that's because economic conditions here have been more favourable. But yet it does suggest a trend that local brands need to be aware of, the swing away from electronic media to more locally focussed media. People want to know what's happening around them and want products and services advertised which are relevant to their daily lives.

Image from David Carson's Fotografiks, courtesy Ginkopress

31 May 2005

You might have thought this was branding.

Here's what happens when a law firm decides that it has a brand.

We were curious when we picked up Friday May 27 Australian Financial Review, "Gadens' brand: you have to laugh", to read that Australian law firm Gadens has gone out on a limb and said that unlike most law firms, "We actually are different and we prove that by behaving differently".

According to Managing Partner, Michael Bradley, at the firm's Sydney office, Gadens is known for its "irreverant and relaxed" culture. Well we went looking for it. And here's why.

Last year we were approached by a large second tier law firm looking to rebrand and reposition. We were excited at such an opportunity and did some extensive benchmarking on Australian law firm brands. An opportunity was ripe for the picking. We did the right thing, flew out to the meet them at our own expense, wrote a lengthy proposal, providing them with plenty of evidence that law firms (let alone most profeessional services firm) don't know how to differentiate themselves, let alone how to brand, and then waited. And waited.

Sure the Managing Partner and his marketing manager thought it was a great idea but he'd have to get it through all the partners in the firm, and he really wasn't prepared for anything even closely resembling evolution. We pitied the marketing manager.

So let's hand it to Gadens. Internally their brand activities concentrate on developing a unique culture, which will inherently serve to enhance and develop distinct brand attributes such as irreverence and ease and which will differentiate it from most of its competitors. And they are making attempts at reflecting this in their recruitment advertising. But is this just the activity of their Sydney office, because we see no evidence of this brand position in what is a crucial part of brand articulation - their website - nor in their visual articulation - their look and feel.

Here's a sample from 'About Us' on their company website:

With more than 85 partners and 720 staff throughout Australia, Gadens Lawyers has the infrastructure and resources to partner with clients at local, state and national levels. Importantly, as the only Australian member of the International Lawyers Network - one of the world ’s largest associations of independent legal firms - we have access to 80 high-quality, full-service law firms with over 4,200 lawyers world-wide. The Network provides clients with easily accessible legal services in 61 countries on six continents.


So where does it say they are "irreverant and relaxed"? We couldn't find any jokes on the site and even Michael Bradley's own bio is more reverant than irreverent.

So, we think this is what happens when a firm only does part of the job of branding [or is there more on the way?]. Perhaps this was a publicity exercise and perhaps they are not what they seem, but branding is much more than an exercise. It is completely holistic and it should, as Gadens does in part understand, permeate the entire organisation and be part of all its communication. It's an idea we're still waiting for companies like Gadens to embrace. So for now we will just have to wait and see.

14 May 2005

Guess who has no idea?

NoIdeaAstroGloTee

Advertising agencies have been put on notice, again. Be ideas companies or disappear.

That’s the latest warning delivered at last week’s annual American Association of Advertising Agencies management conference.

According to the New York Times, what clients want most from their agencies is "the power of the big idea”.

“Yet that is probably a phrase that makes every agency cringe because there's no clear path to get to it”, said president and chief executive of Volvo Cars North America division of the Ford Motor Company, Anne Bélec.

Generating bigger, better ideas was also on the mind of another speaker at the conference, MDC Partners Toronto’s chairman and chief executive, Miles Nadalat, a devourer of creatively focussed advertising agencies across the States.

"The challenge for our industry is to make advertising a business of ideas instead of a business of ads and their distribution" said Nadal.

"What clients want most are ideas, innovation, creativity," he added.

While all too often agency leaders have a "focus on money rather than on results for clients", the Times reported.

"The most successful people in this industry are not motivated to come to work every day to make the most profits, but rather to come up with the best ideas.”

Now how many people in Australian agencies would dare even say that they’re ideas companies or that they are in the business of ideas? And how many clients, like Volvo, would demand it? Or even pay for it?

Australian ad agencies reflect in part the paucity of demand for inspirational ideas and concepts from clients, combined with their own slavish corporate attendance to the bottom line. Tell us any different.

No Idea Astro-Glo T-shirt image (c) www.contagious.com

04 May 2005

Why we're scared of brand "narrativism".

According to Iconoculture's latest Iconowatch (www.iconoculture.com) the new word for brand narratives or brand stories is "narrativism". While we're very happy that the idea of a brand narrative is starting to seep into general discussions of brand and more importantly, into people's understanding of how complex brand structures and stories evolve, we're more worried about the use of words that don't exist or are innaccurate.

"Narrativism" is not in any dictionary we could find. The closest, according to our Shorter Oxford, is NARRATIVITY viz. "the quality or condition of being or presenting a narrative; (the action of story-telling)". As a verb it could be NARRATIVIZE "to present or interpret in the form of a narrative"

In a wider context, if the people at Iconoculture mean "narrativism" to mean "to tell our tales, cobbling together bits of promise from a scattershot of brands and products to create our own complex consumer tale" they may also be referring to the application of French semiotics term often used in the analysis of subculture BRICOLAGE, "the construction or creation of whatever is immediately available for use".

Understanding brands and branding can only be made easy for people if, as George Orwell always maintained, we use words that speak clearly and accurately project meaning.

22 April 2005

Go forth and multiply.

International clothing retailer Gap has finally officially announced “Forth & Towne” is the name of the company’s new women’s apparel retail concept. We got wind of this a couple of weeks ago when I was in New York, talking to various fashion industry insiders. It comes as no surprise that Gap, along with many other retailers, are looking to target an older and more wealthy demographic, the Boomer.

According to Forth & Towne President Gary Muto, the name was chosen because “we wanted it to evoke a sense of place - to signify a special and unique shopping destination.”

'Forth' references our fourth brand, and 'Towne' conveys a sense of community that we want to create for our customers when they shop with us,” added Muto.

Unsurprisingly the intention to develop the new brand was announced last year. It’s intended to target women over the age of 35, a rapidly growing segment of the population. Apparently this group’s spending power accounts for about 39 percent of all US (we assume) women’s total apparel expenditures.

However, we also understand it’s really Gap Inc’s attempt at targeting women closer to 55, the mind-numbing Boomer market.

We’re not sure of the validity of being so self-referential as to name your new brand after the fact that it’s your Fourth (alongside, Gap, Banana Republic and Old Navy) and we’re not so sure of the idea that 'Towne' will create that old special feeling of an old city style neighbourhood department store, especially since Gap-like stores helped push to closure these very same neighbourhood department stores by locating to edge of town malls.

Still, they are trialling the concept in four locations in Chicago and New York. And that’s for starters.

Gap Inc also announced that they trying to refocus the old Gap brand into something more “fresh and relevant”. They’re even looking at franchise models as they continue their international expansion (think China). Our recent experience is that it’s hard to even find a good t-shirt in the store. James Perse having long ago taken that mantle from the Gap stores by doing it so much better.

01 April 2005

Granola name finally packs a punch.

We hear the Sanitarium Food Company here has started coming down hard on the users of the name "Granola", forcing many Australian companies who use it to remove the name and the offending products from supermarket and deli shelves. But as a name it has something of a spotted history and it maybe that Sanitarium may find itself on crumbly ground.

According to foodreference.com, the origins of "granola" date back to 1863 and the work of Dr. James C. Jackson of New York. Jackson developed what he called "Granula", a Graham flour formed into sheets, baked until dry, broken up, baked again and broken up into even smaller pieces. In 1855 at the Battle Creek Michigan headquarters of the Seventh Day Adventist Church, their Sanitarium director Dr. John Harvey Kellogg (later to found Kellogg's) was experimenting with foods and one of his developments was a breakfast food of whole grains, baked and ground up, which he named "Granula". He was later sued by Dr. Jackson for copying the name, so he renamed his concoction "Granola"!

Kellogg lost interest in cereals for a while, and turned his attention to nuts, and "Granola" as he named it never became a commercial success. But the Granola name was revived by the modern health food movement and it became a health food in the 1960s.

So what is it with generic names? Companies may have to check out licensing arrangements for common names. We think it's a little like wine and cheese naming. And when do names become so generic that they are no longer the property of their inventors - take band-aid and hoover, for instance. We think the difference is in the active appropriation and exploitation of the name.

Sanitarium claim they trademarked the name in 1921, so why does it take them over 80 years to act on it? Is this the forerunner to a new marketing campaign for Sanitarium Granola? We haven't heard of similar activity in the USA, but we'll let you know.

Now we're waiting for the Bircher company to claim the "Muesli" name. "Muesli" was developed in the late 19th century by Dr. Bircher-Benner, a Swiss doctor and nutritionist. And we always thought it was just a type of muesli.

18 March 2005

Minority vision.

enlarge50

Australia's Eyecorp are trying to build new opportunities to spread advertising. Their latest foray is in shopping mall broadband streaming advertising. According to AAP, Eyecorp is set to launch Prestige Plus, a network of more than 75 individual digital display units in 17 shopping centres in Sydney, Melbourne and Brisbane.

Similarly, Amsterdam's Schipol Airport has just launched the Event Screen Lounge. According to Schipol Media, the Event Screen consists of two different screens which can interact with each other, with the largest screen being 20 m2.

Along with Frankfurt Airport, Schipol is probably one of the world's most media saavy airport organisations. We're still waiting for the others to catch on!

We're evangelists here at DIFFUSION for the wired/unwired world of streaming advertising, after all we've been working in this field for sometime. See what we think about what we call, 'Immersive Marketing' at www.diffusion.com.au Press Articles.

Why airports are more than just transit hubs.

The US Federal Aviation Authority (www.faa.gov/news) this week announced that it expected more than a billion people to be travelling through US airports within 10 years. What it didn't say was that people were likely to be waiting for longer periods, as airport owners and authorities struggle to provide the necessary infrastructure that will be required to meet the anticipated demands.
We think that airports need to start considering that they are on the brink of a radical change in their status as transit hubs; needing to provide more services as consumers become 'transumers'. Service infrastructure will need to replace the current shopping mall mentality as people begin to demand a more compelling airport experience, or at least service experiences similar to those they can find at home. Those hubs that are unable or unwilling to meet this need, will find usage flagging.

Not so $mart: Coles Myer's name game.

smartbuy_large

Not much is really new at Coles Myer. This Smart Buy brand has already been operating in south-western USA food stores for some time.


When Australia's largest retailer and biggest company, Coles Myer, announces to the sharemarket (www.colesmyer.com.au) that it intends renaming and relaunching its homebrands for its Coles supermarkets, you would expect that this would be handled with some level of sophistication and perhaps even evidence of consumer research. Modelling itself on the success of Britain's Tesco and Sainsbury's own homebrands, you'd also think there would have been some real thinking and research in the naming of the new lines. Even more importantly, Coles expects that the renamed homebrands lines will generate 30% of all sales by 2007. Worth billions.

So here are the new names - a budget label 'Coles $mart buy', a mid-priced line 'You'll love Coles' and a premium brand, 'George J Coles', named after the company's founder. Now we love 'George J Coles', but the rest?? Is 'Farmland' a better or worse name? A three tiered home brand line is a sensible policy, but it's also got to be seen as something serious, something that is going to feel like an attractive proposition to customers. Not merely a slogan.

Worse still is John Fletcher's idea for a name for a new liquor category killer to take on Woolworth's hugely successful Dan Murphy brand superstore. '1st Choice'. What does that mean? Like Megamart, the electric superstore, it means nothing and consequently has no way of building an identity, let alone, a brand.

Let's hope the result for Coles Myer won't be the same as when they dumped all the equity associated with the Grace Bros name in NSW and replaced it with the name Myer; a move that has still not managed to arrest falling sales and a flagging brand.

The question is, on what basis does Coles Myer makes these kinds of decisions?

16 February 2005

Dissenting voices.

This just in. And we think it's telling us how seriously corporate America is taking blogging as an anti-corporate voice.


"CooperKatz & Company, New York, opened a practice called Micro Persuasion intended to help corporate clients monitor and respond to issues that circulate on blogs and other online venues. Steve Rubel, vice president for client services, was named to lead the practice."

New York Times "In Advertising Webdenda"
Wednesday, 16 February 2005